
Options Strike Selector — Breakeven vs Expected Move (AR/EN)
Compare each strike's breakeven to the expected move before you buy.
Traders often buy far out-of-the-money options because the premium looks cheap — then the big move never arrives and the premium expires worthless.
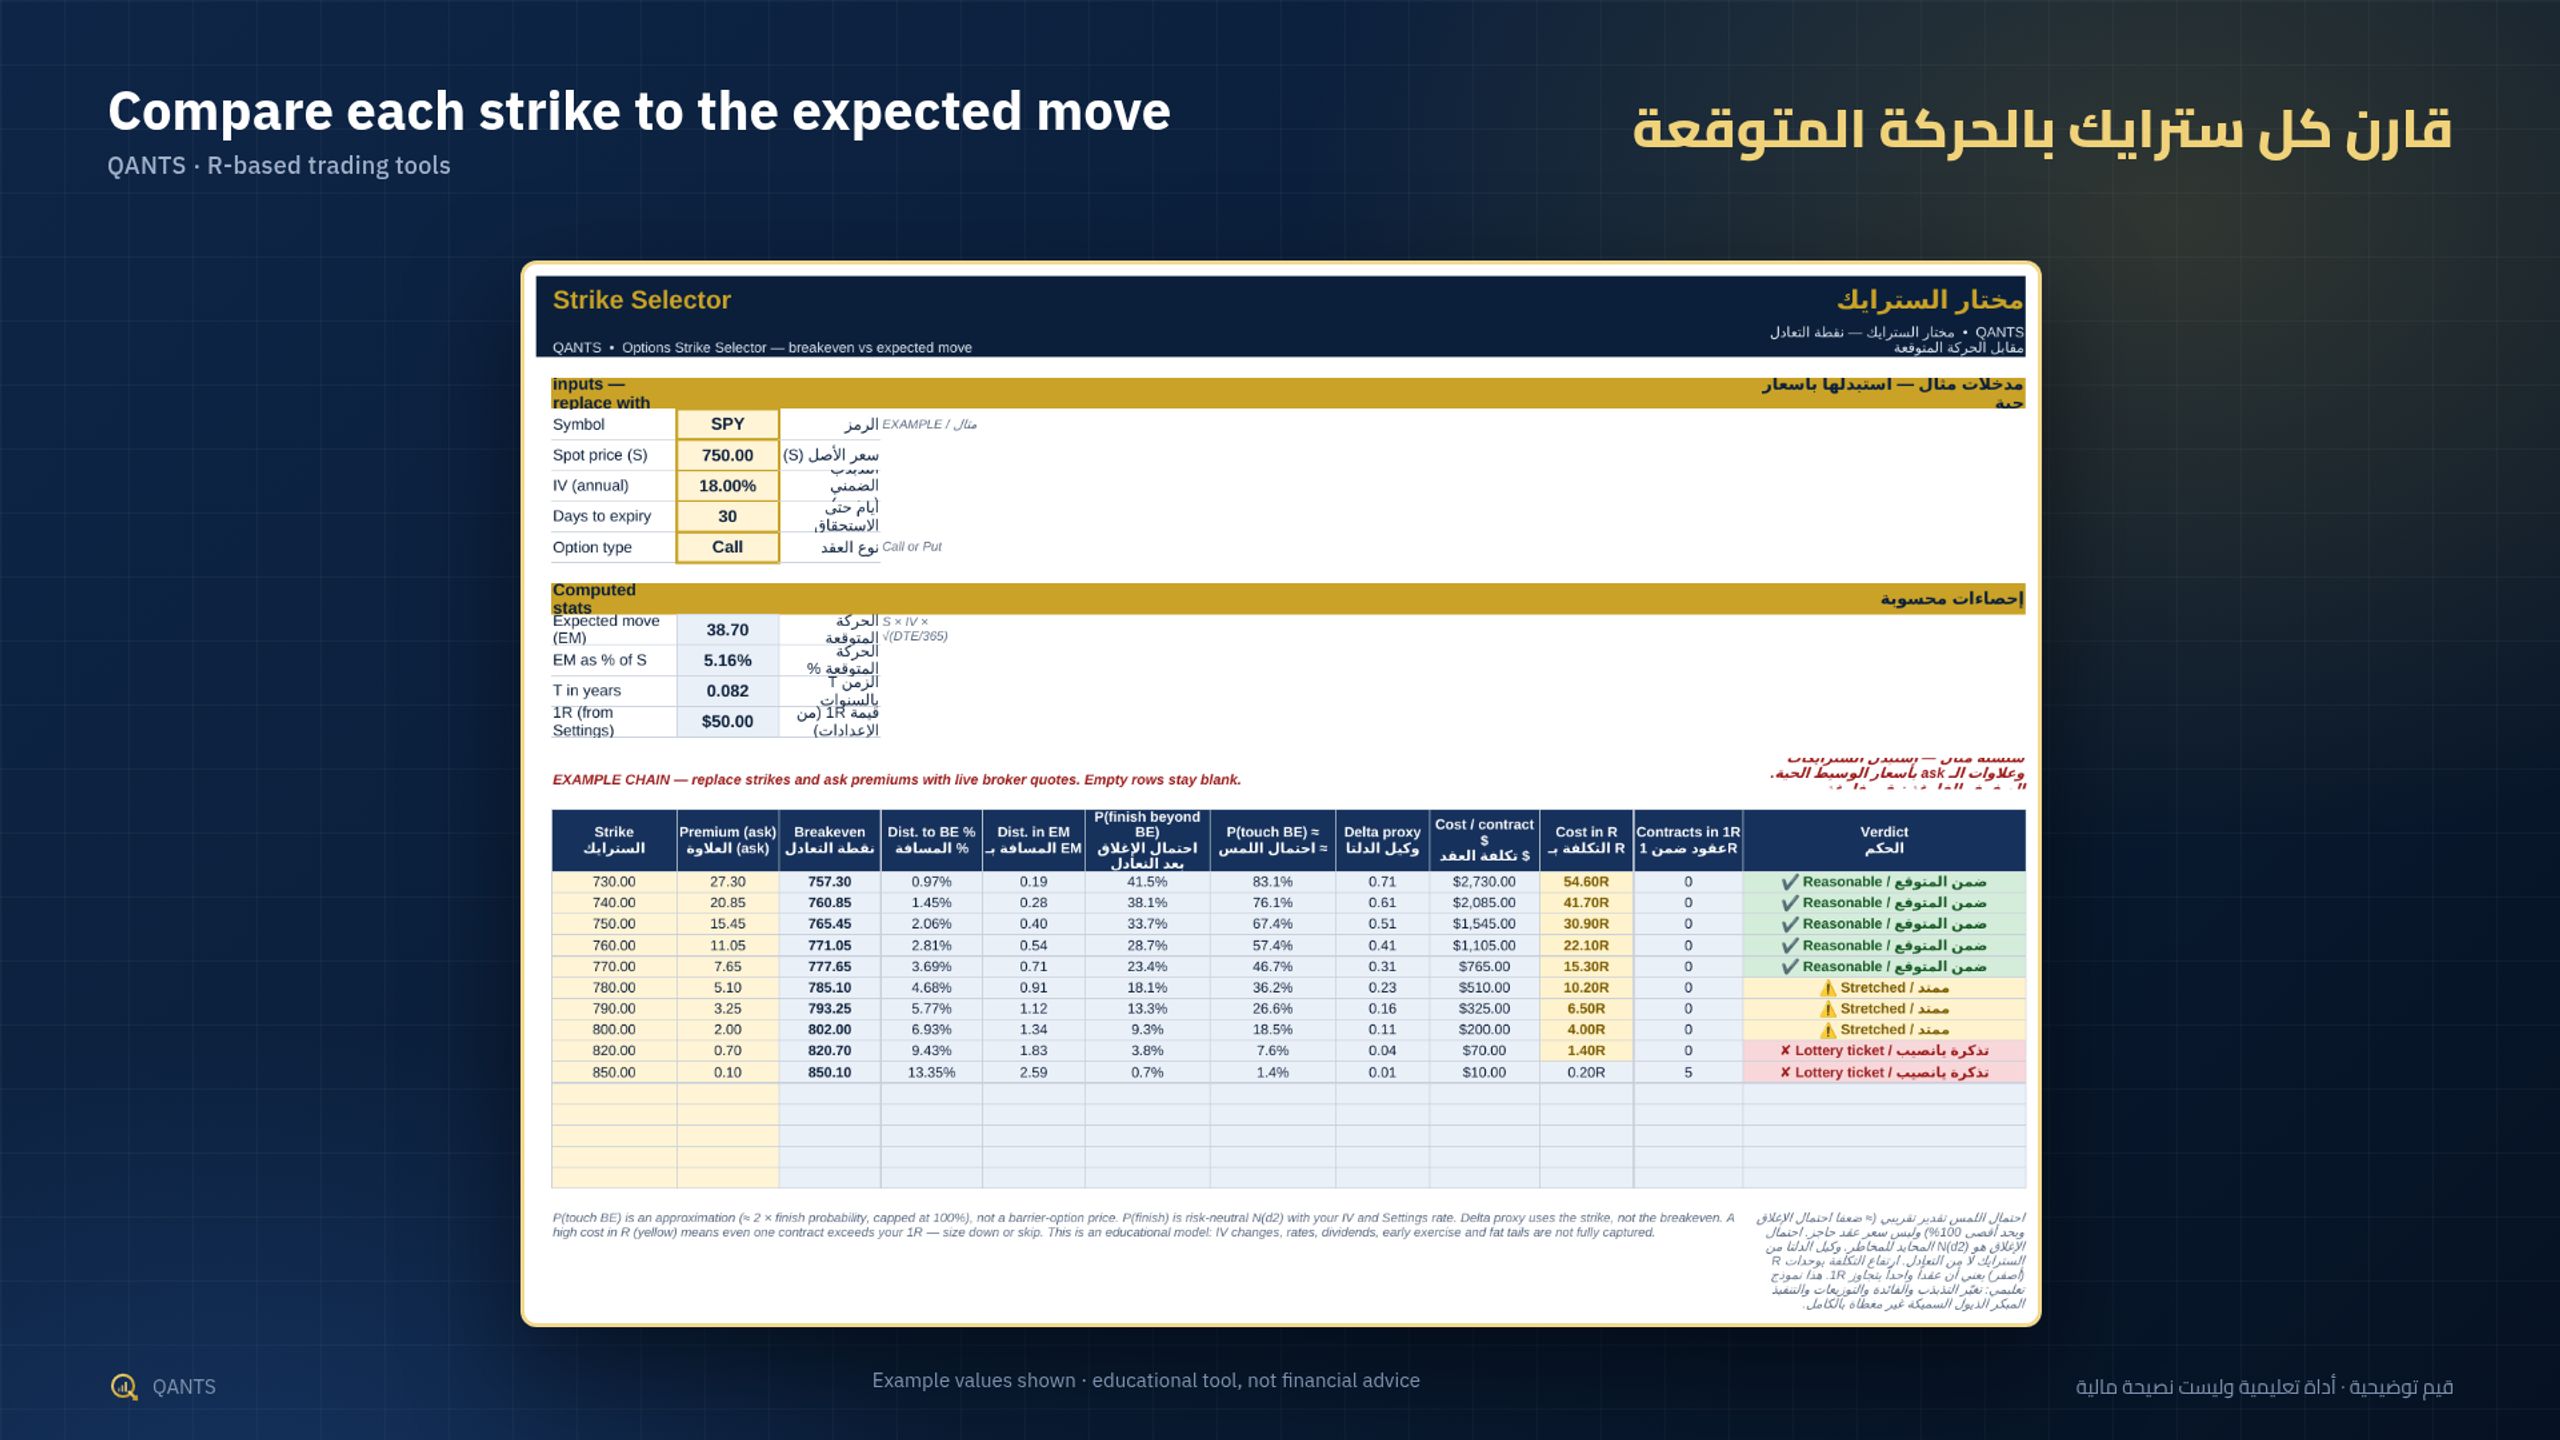
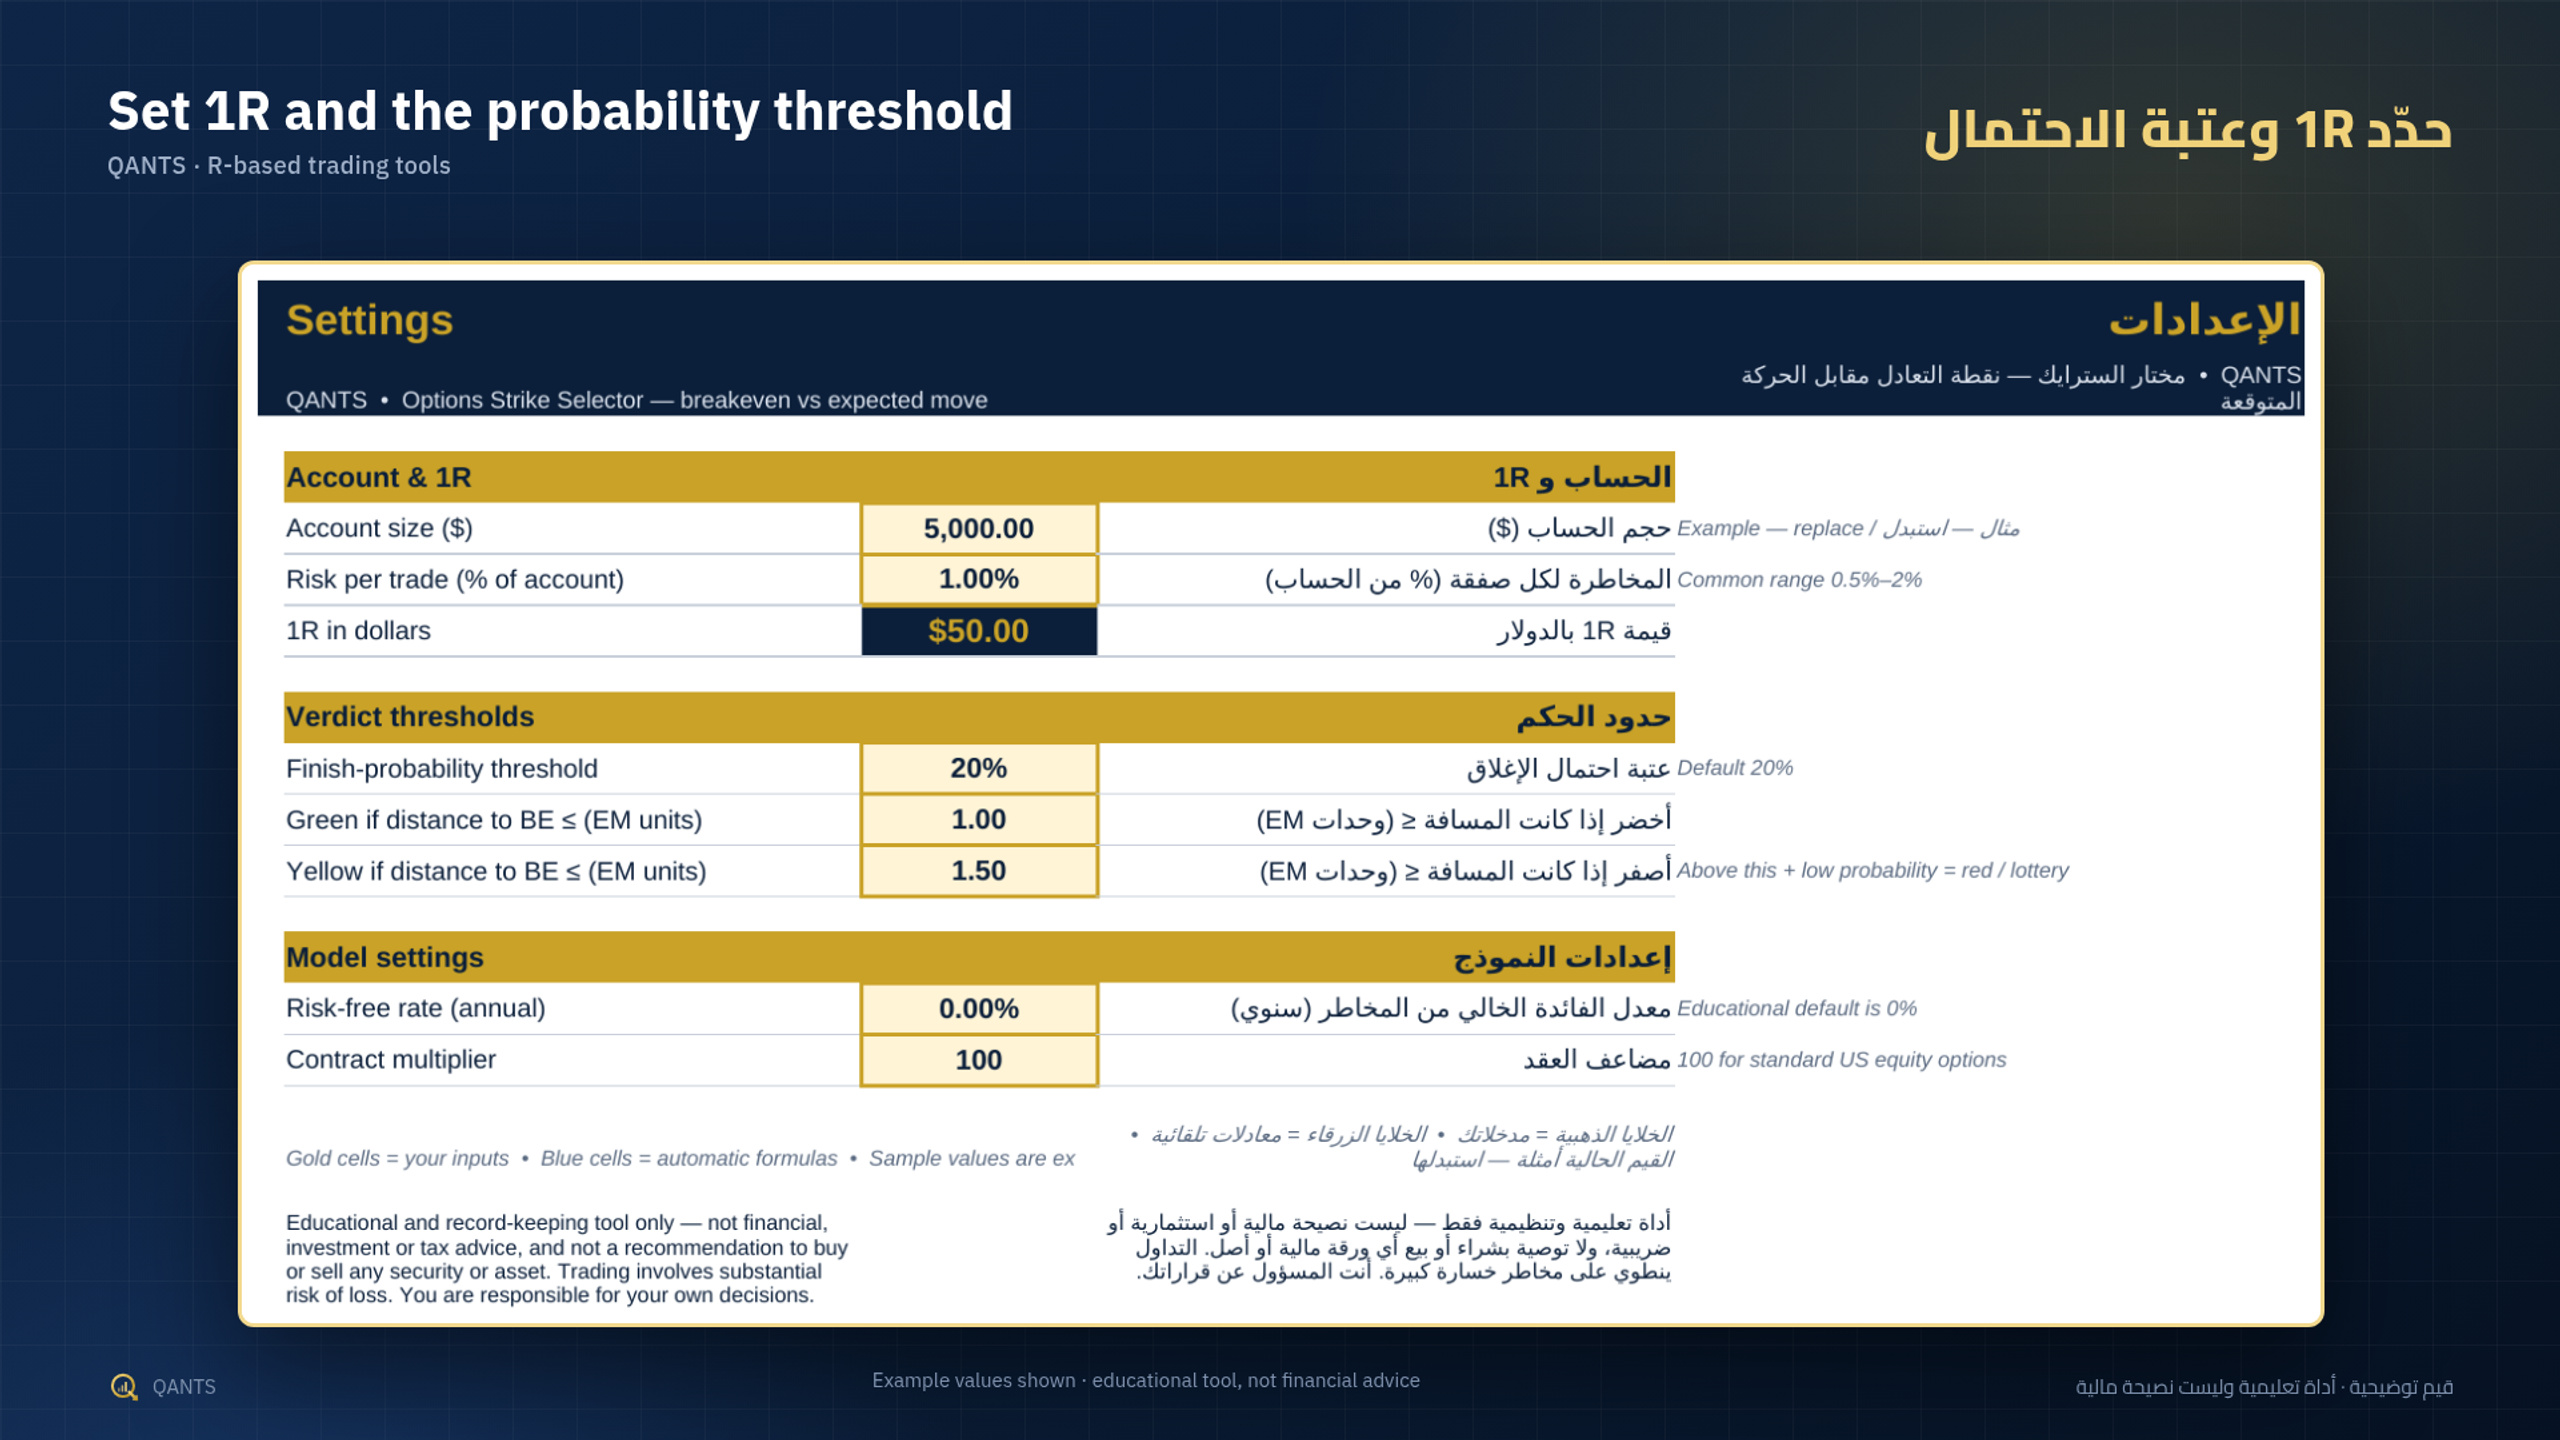
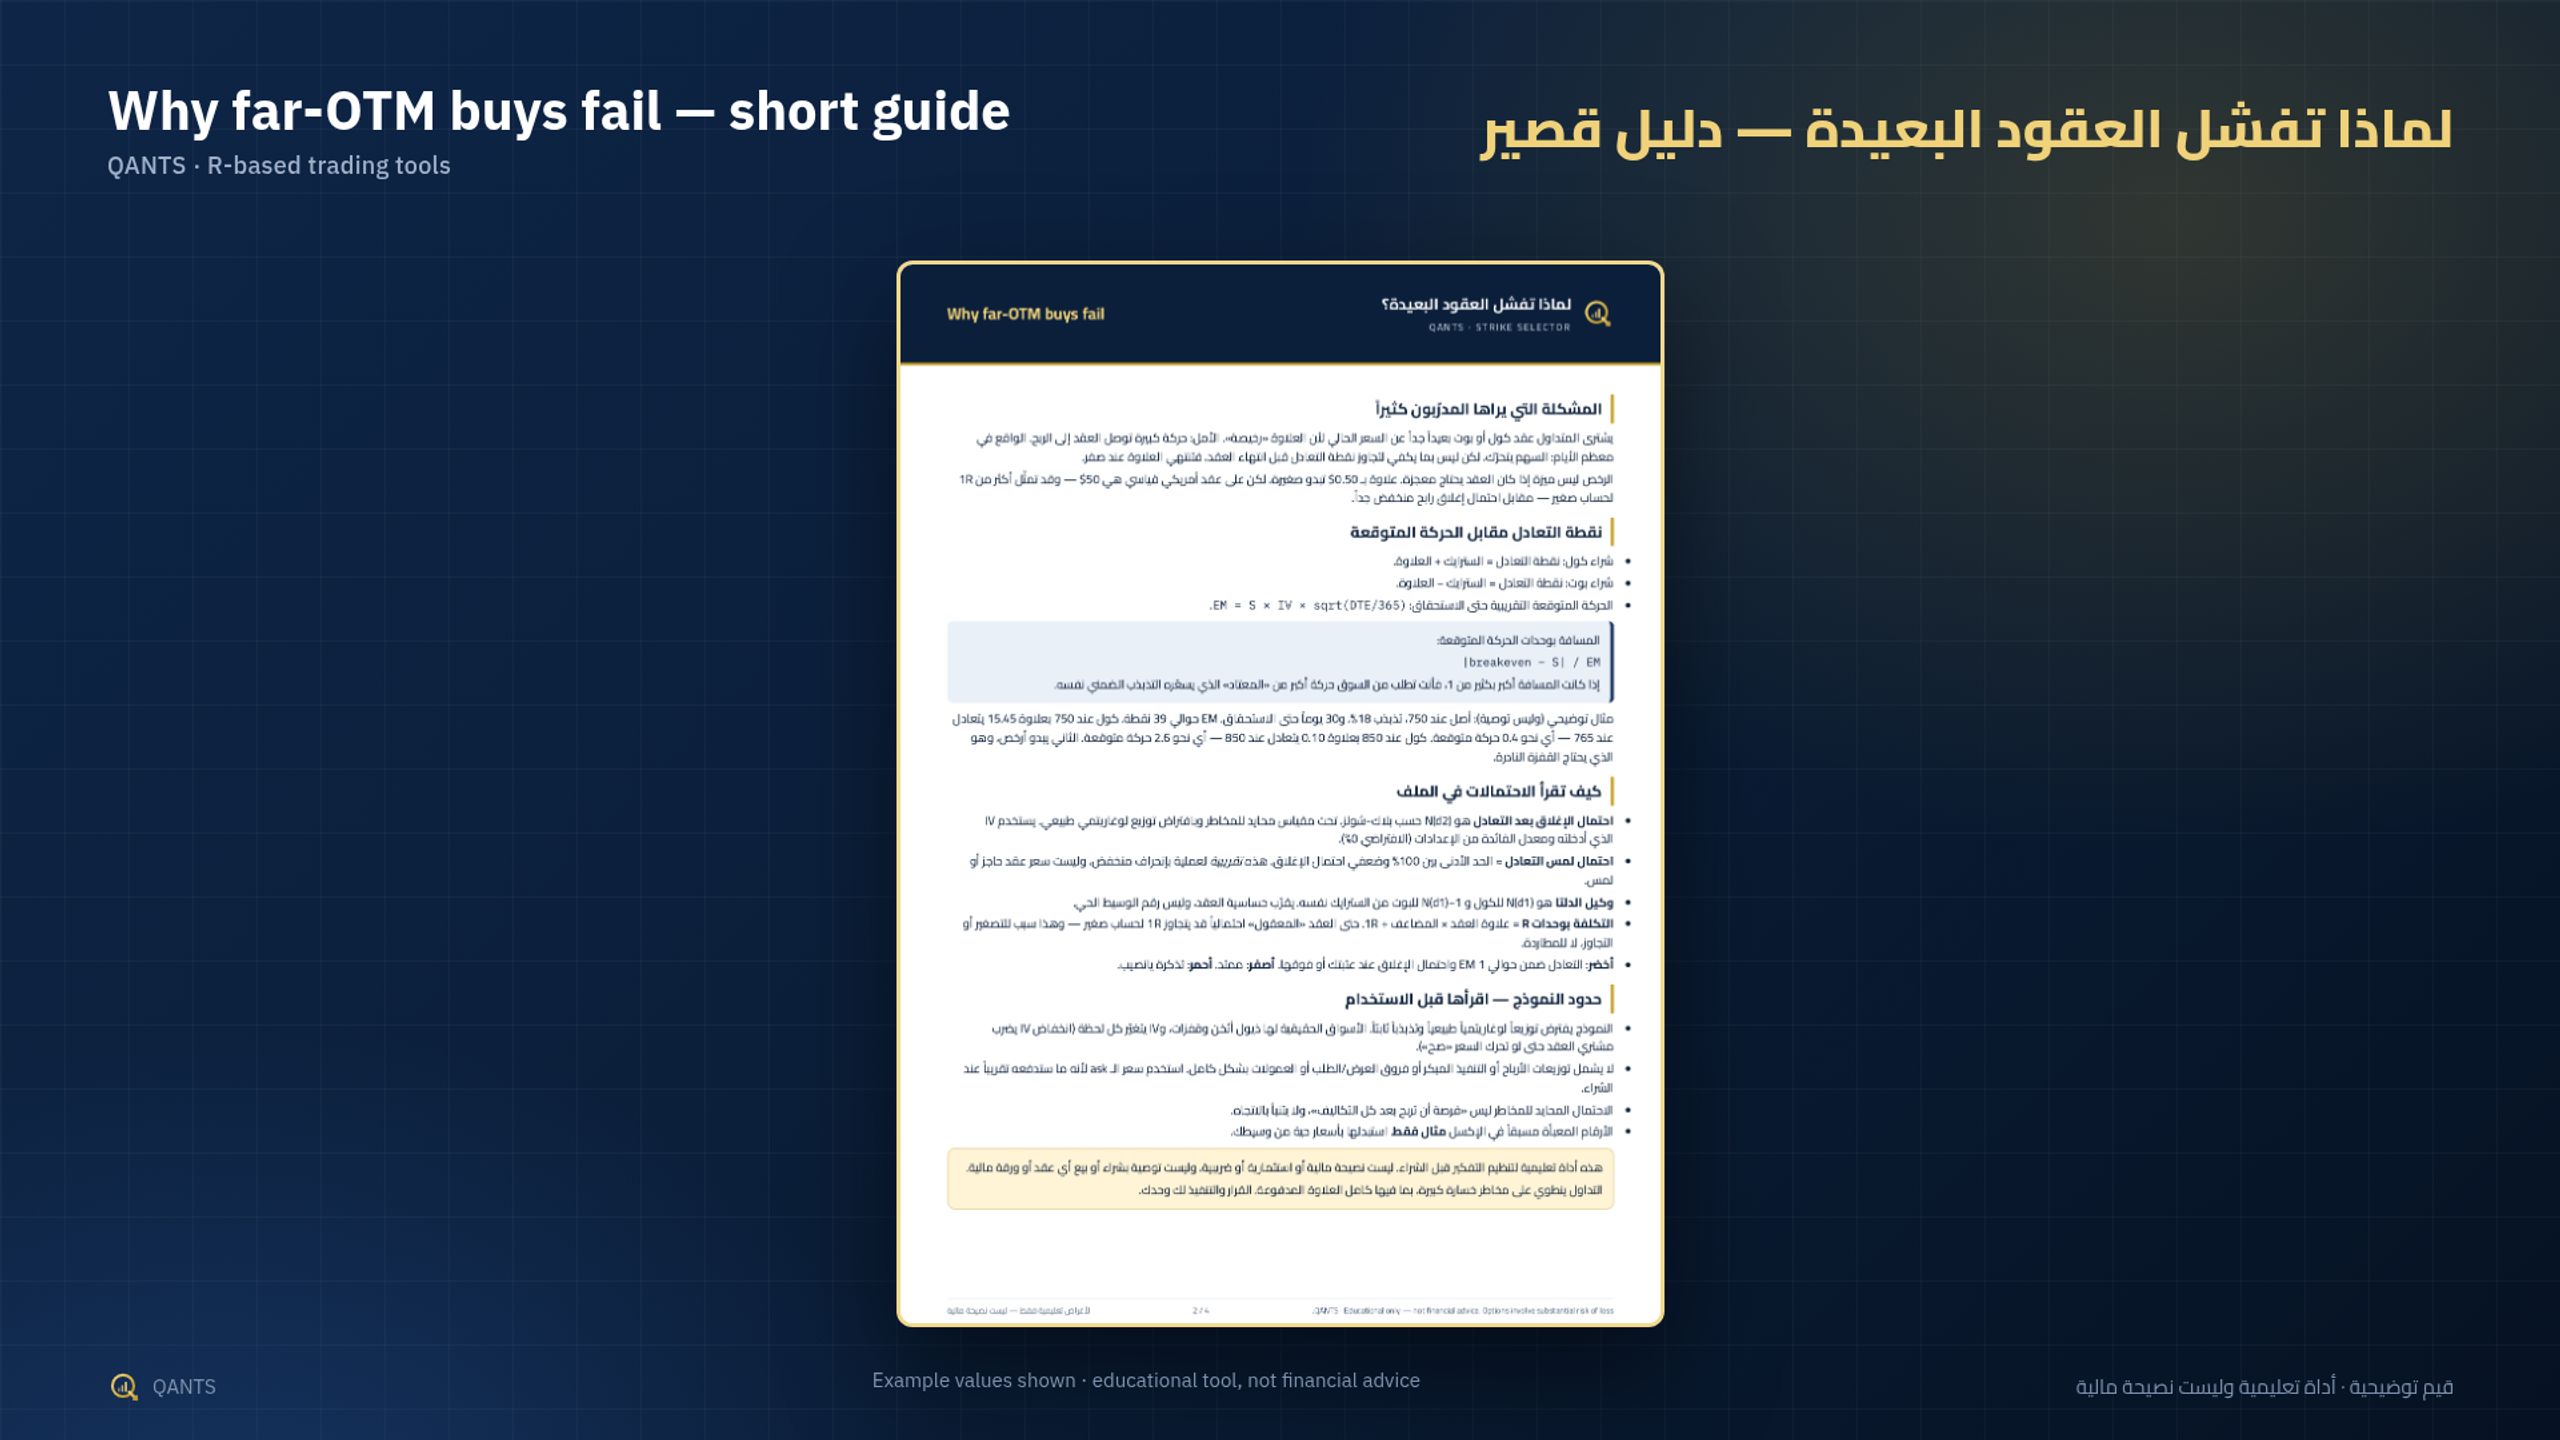
This bilingual Excel workbook (Google Sheets compatible, no macros) compares each strike’s breakeven with the expected move EM = S × IV × √(DTE/365). Paste strikes and ask premiums to see, before you buy: breakeven, distance in % and in EM units, probability of finishing beyond breakeven (Black–Scholes N(d2)), an approximate chance of touching breakeven before expiry (~2× finish probability, capped at 100%), a delta-style proxy, cost of one contract in dollars and in R, and a colour verdict (green = within about 1 EM and above your threshold; yellow = stretched; red = lottery ticket). Settings hold your 1R and threshold. Sample values are an example — replace them with live quotes. A short bilingual PDF guide (Arabic first) explains why far-OTM buys fail and the model’s limits.
Included: Strike Selector (15 rows) · Settings · Instructions AR/EN · PDF guide.
ملف Excel عربي/إنجليزي يقارن نقطة تعادل كل سترايك بالحركة المتوقعة، ويعطيك احتمال الإغلاق بعد التعادل وتقديراً لاحتمال اللمس، وتكلفة العقد بوحدات R، وحكماً بالألوان. مع دليل PDF قصير. القيم المعبأة مثال — استبدلها بأسعار حية.
Disclaimer: Educational tool only; not financial advice or a recommendation to buy or sell any option. Model probabilities assume lognormal prices and constant IV. Options involve substantial risk of loss, including the full premium paid.