
QANTS Options Chain Filter — Python + CSV (AR/EN)
Filter a chain by liquidity, delta, and breakeven versus expected move.
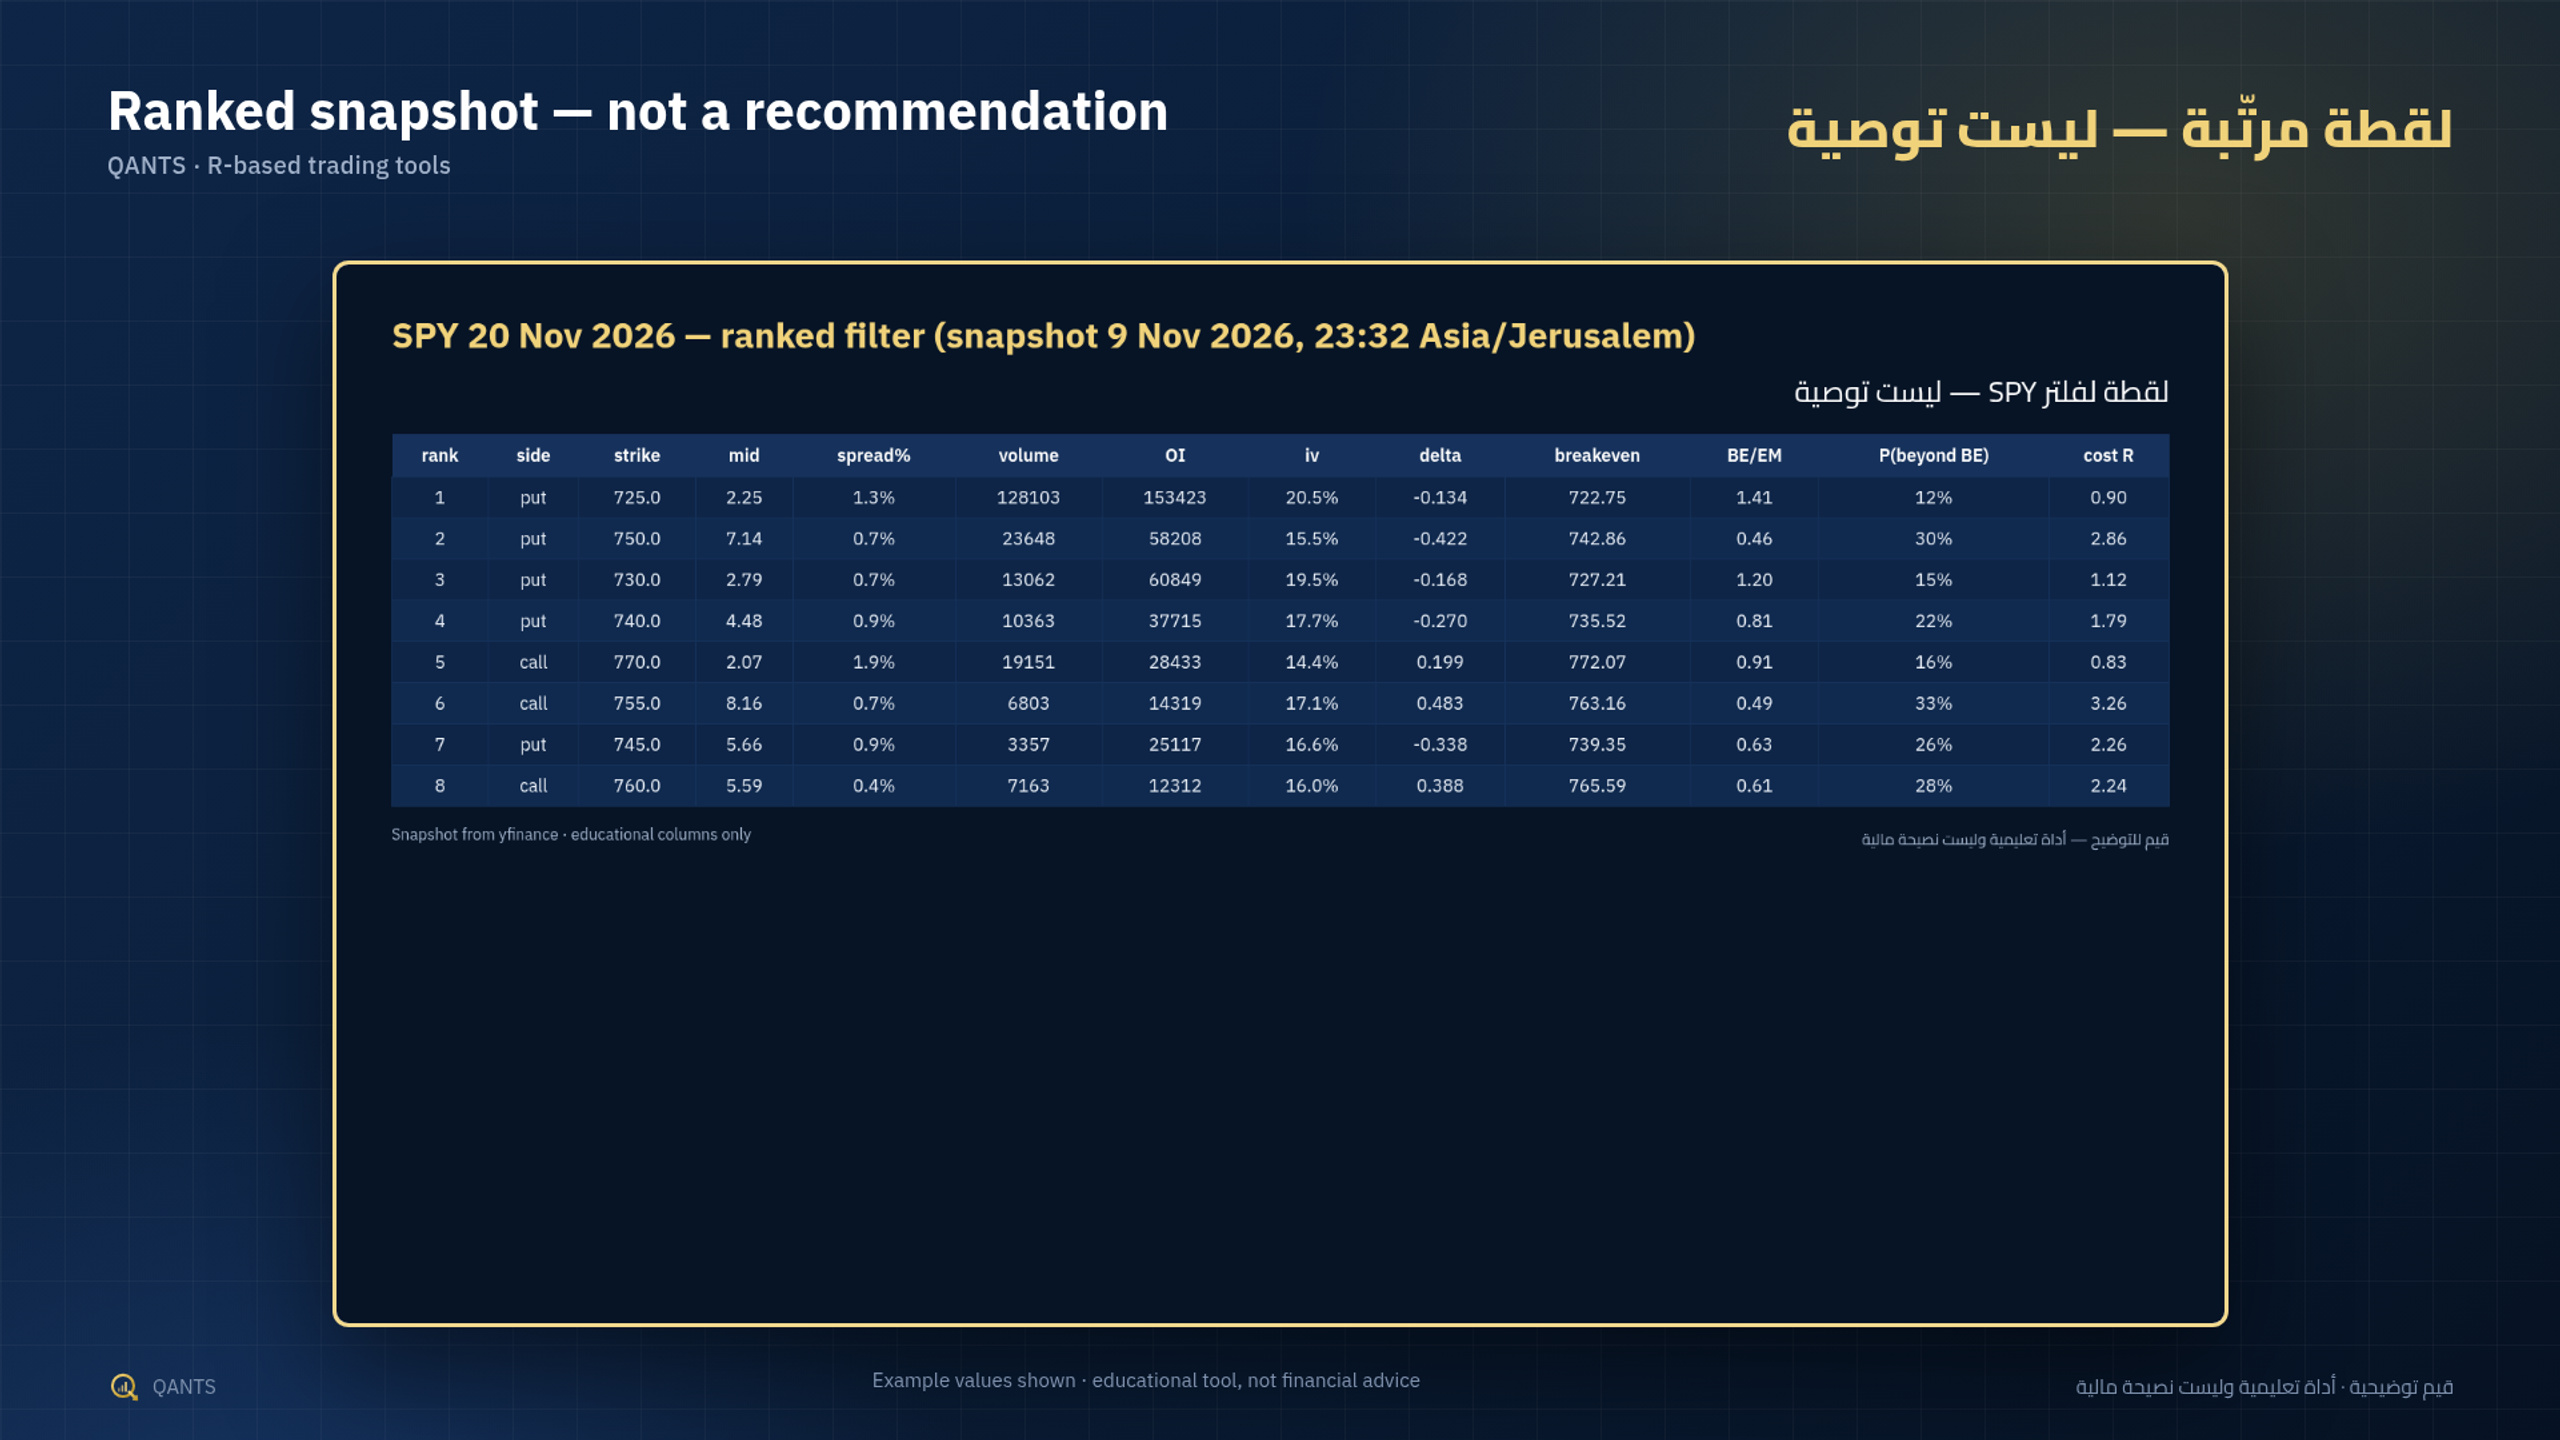
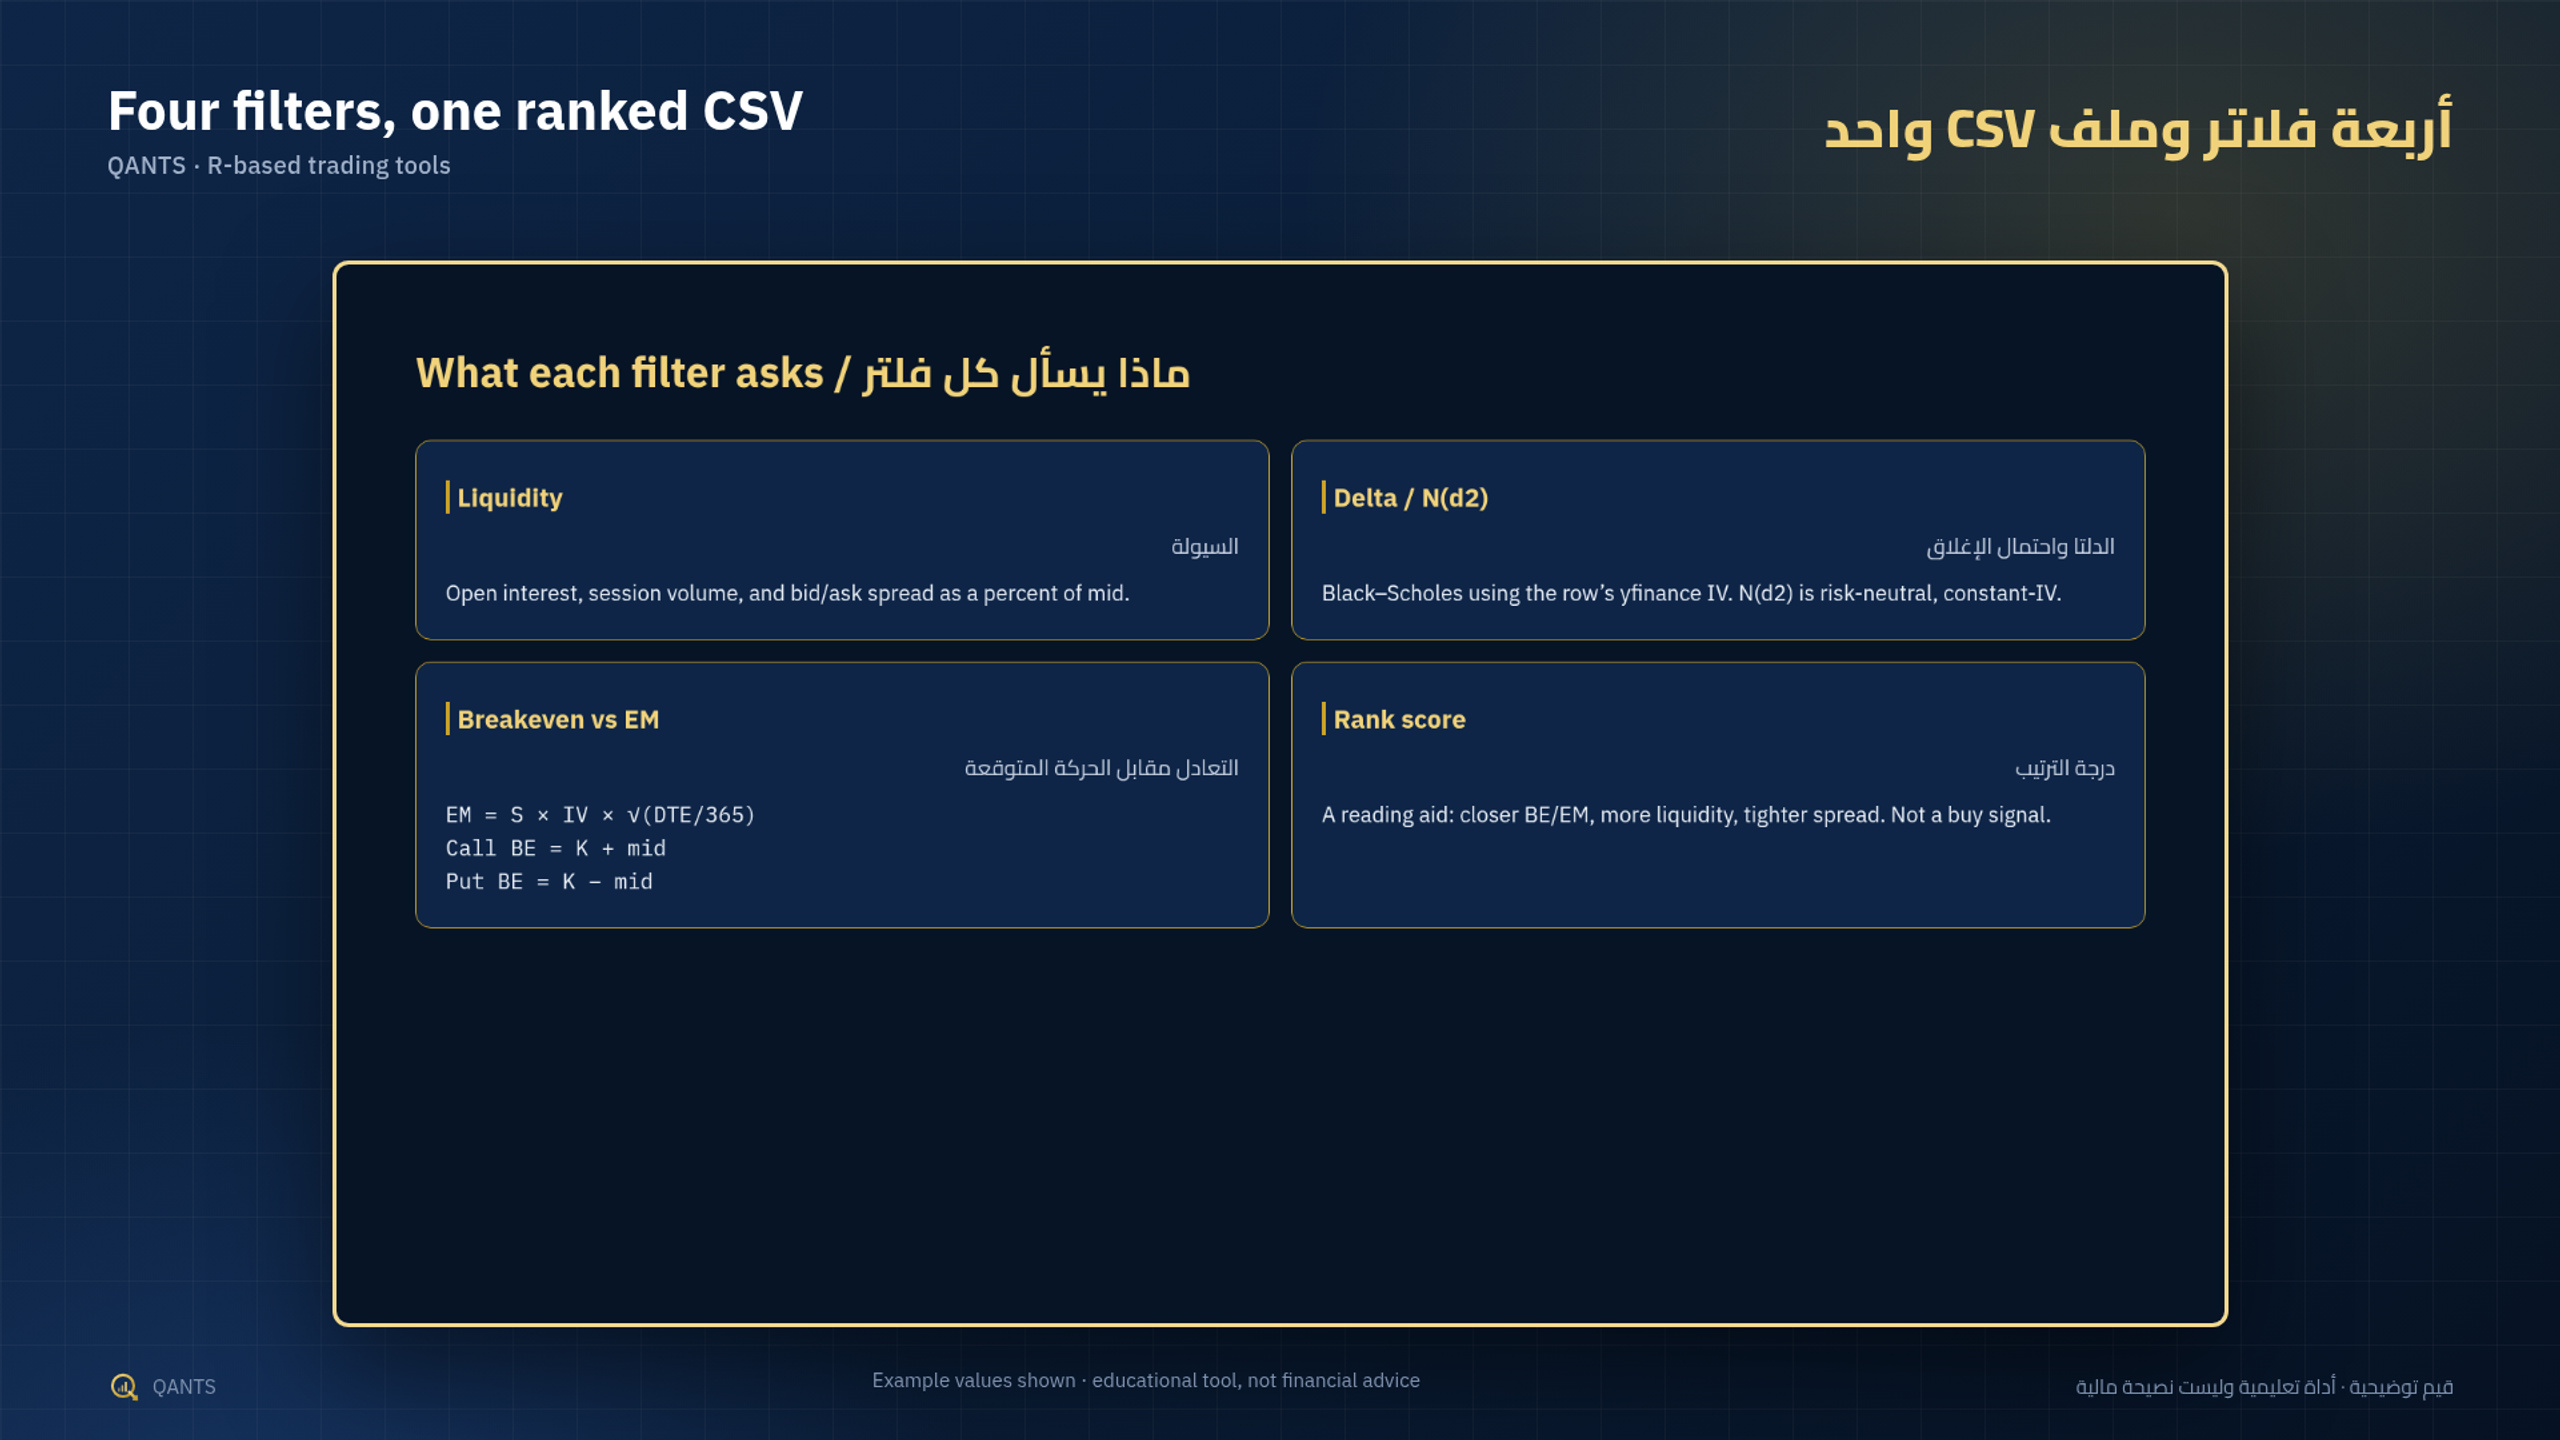
A Python command-line tool that pulls a free yfinance options chain for a ticker and expiry, then keeps contracts that pass filters you set: open interest, volume, bid/ask spread percent, Black–Scholes |delta| (from each row’s implied volatility), and how far the long breakeven sits from the expected move EM = S × IV × √(DTE/365). It prints a console table and writes a ranked CSV. The rank is a reading aid (closer breakeven, more liquidity, tighter spread) — not a list of recommended trades.
Delta and N(d2) use Black–Scholes with your rate and dividend inputs. Probability of finishing beyond breakeven is N(d2) evaluated at that price (risk-neutral, constant IV) — not the chance of touching it before expiry.
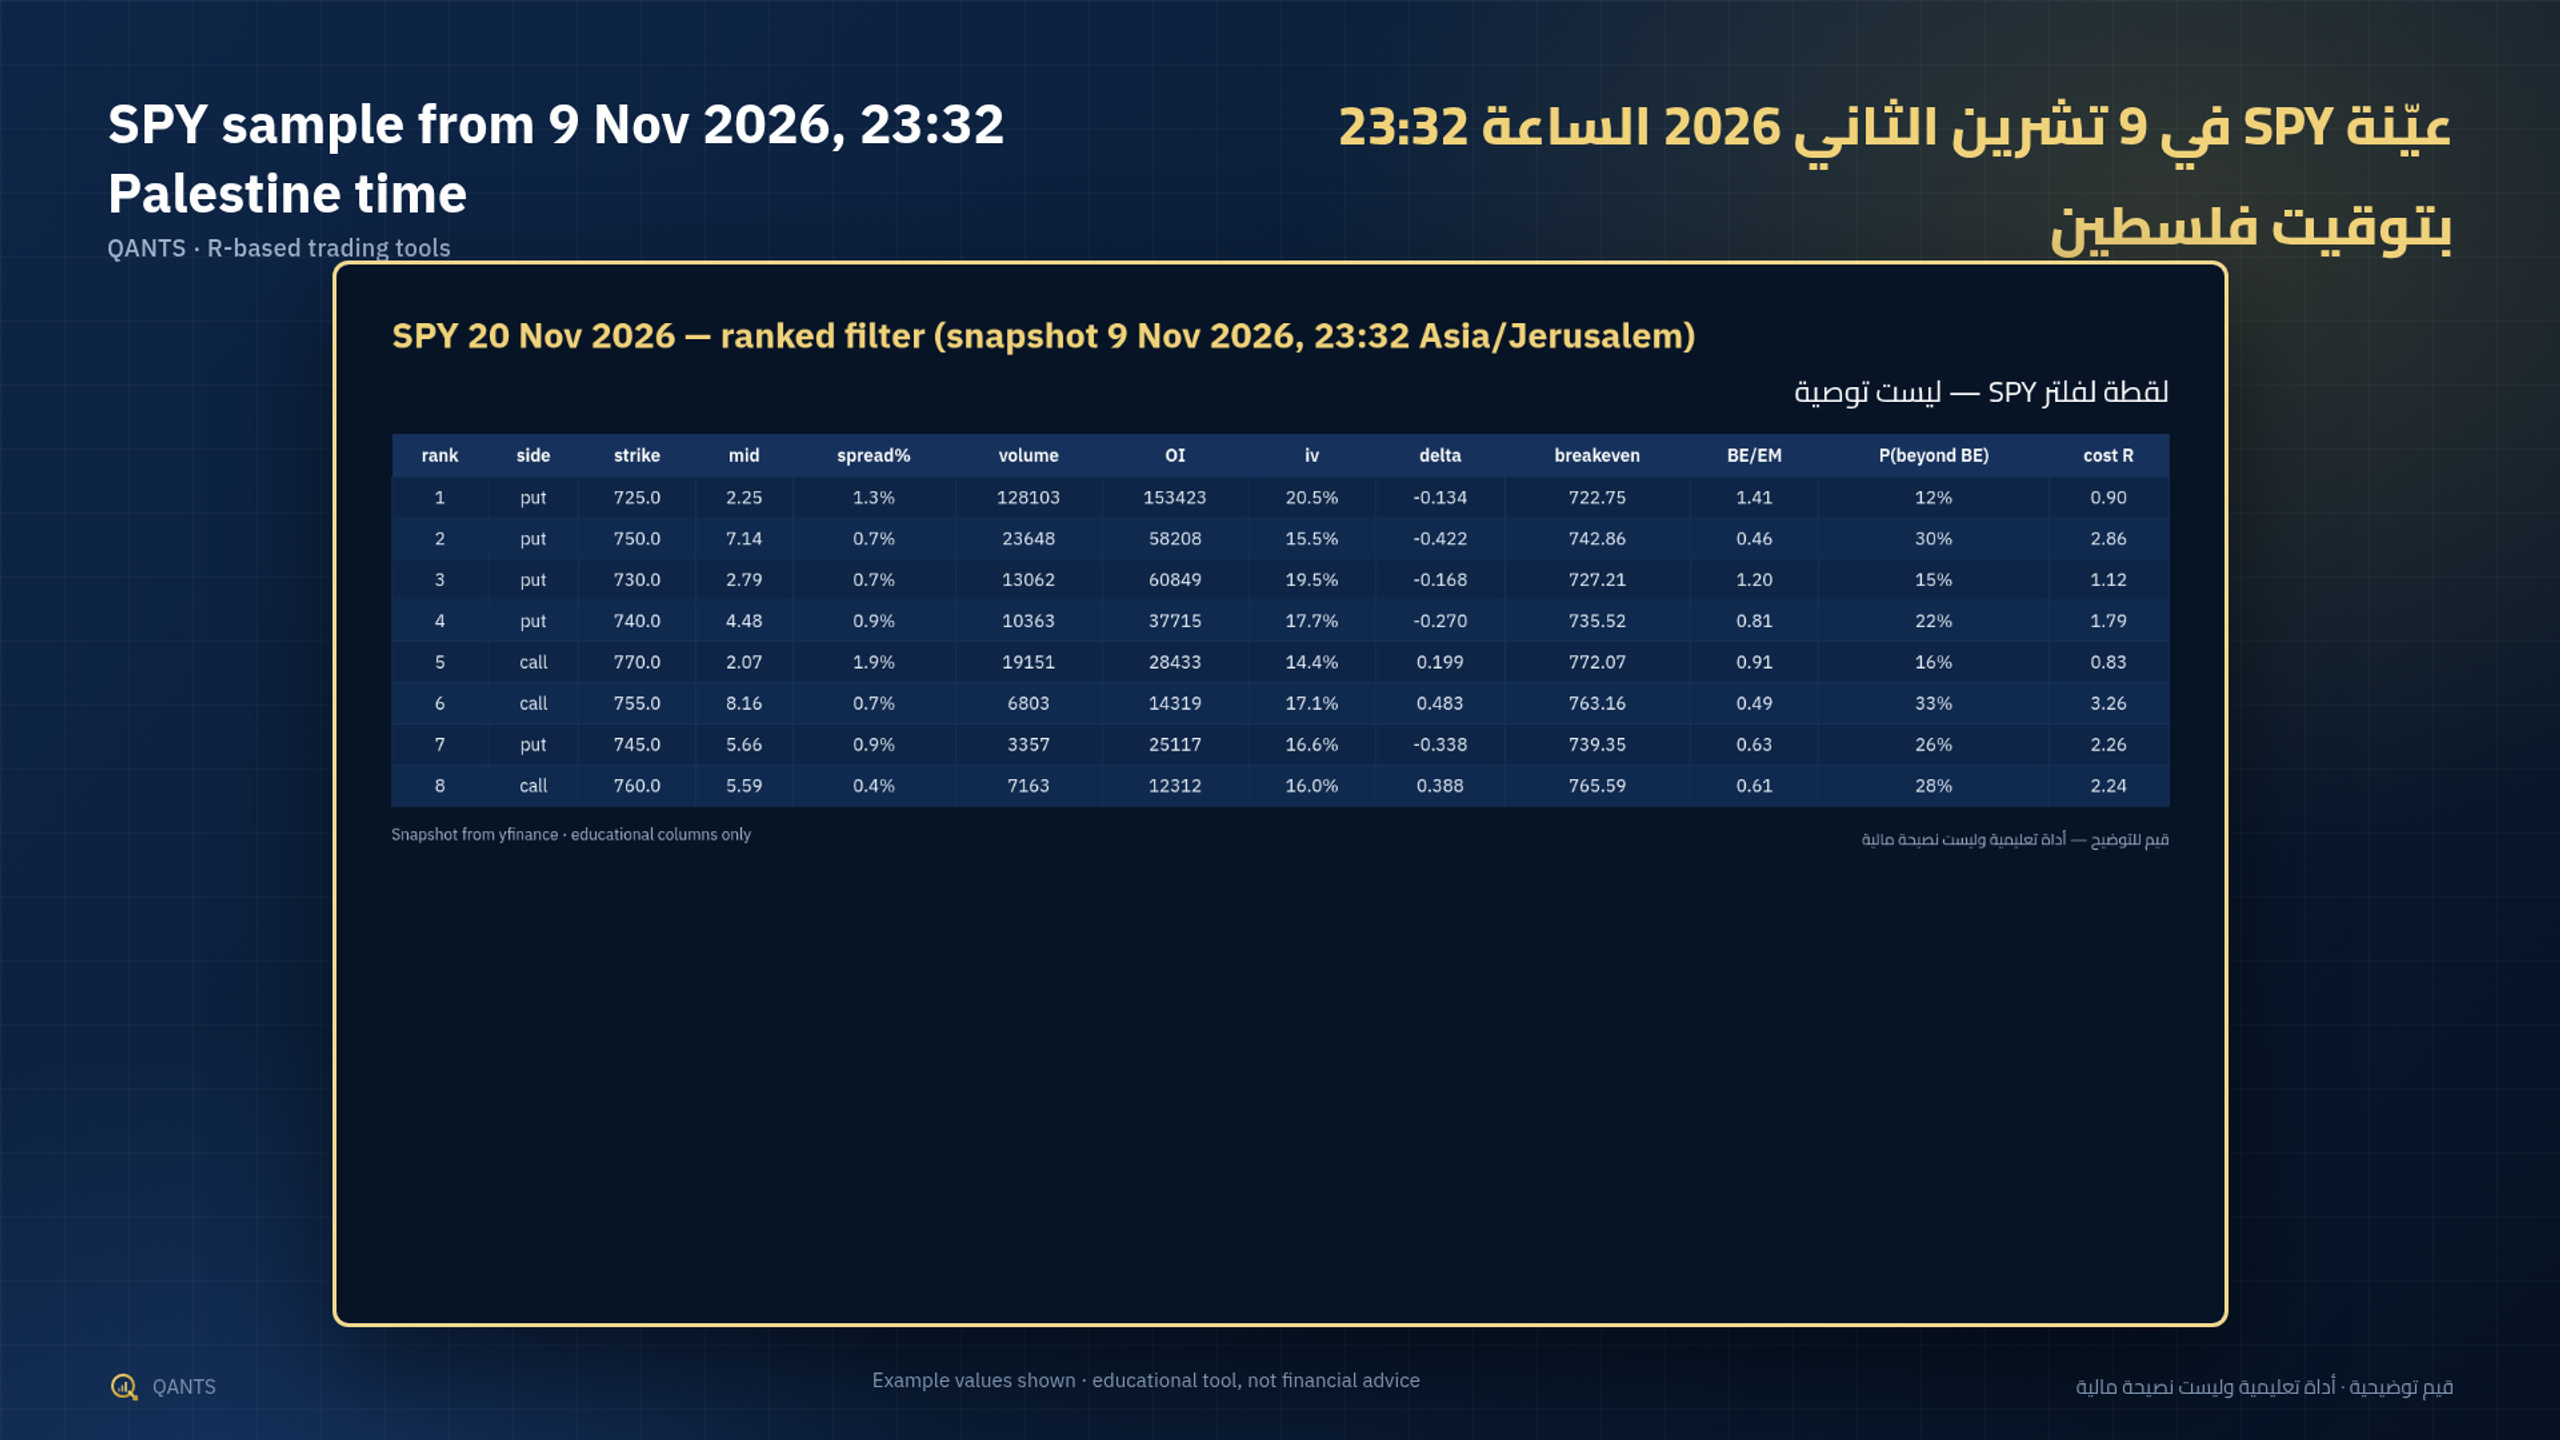
Includes the script, requirements.txt, a bilingual PDF + README, and a dated SPY/QQQ snapshot (9 November 2026, 23:32 Asia/Jerusalem) so you can learn the columns. Run the script yourself for a fresh chain.
سكربت بايثون يصفّي سلسلة الأوبشن حسب السيولة والدلتا ومسافة نقطة التعادل عن الحركة المتوقعة، ويكتب ملف CSV مرتّبًا. العيّنة لقطة للتعلّم وليست توصية.
Disclaimer: Educational tool only — not financial advice. yfinance data can be delayed or incomplete; deep ITM/OTM IVs are often unusable and are dropped. Options can expire worthless. Trading involves substantial risk of loss.