
Quantitative Analysis Toolkit — Factor scores, mean-variance, correlation, VaR
$25
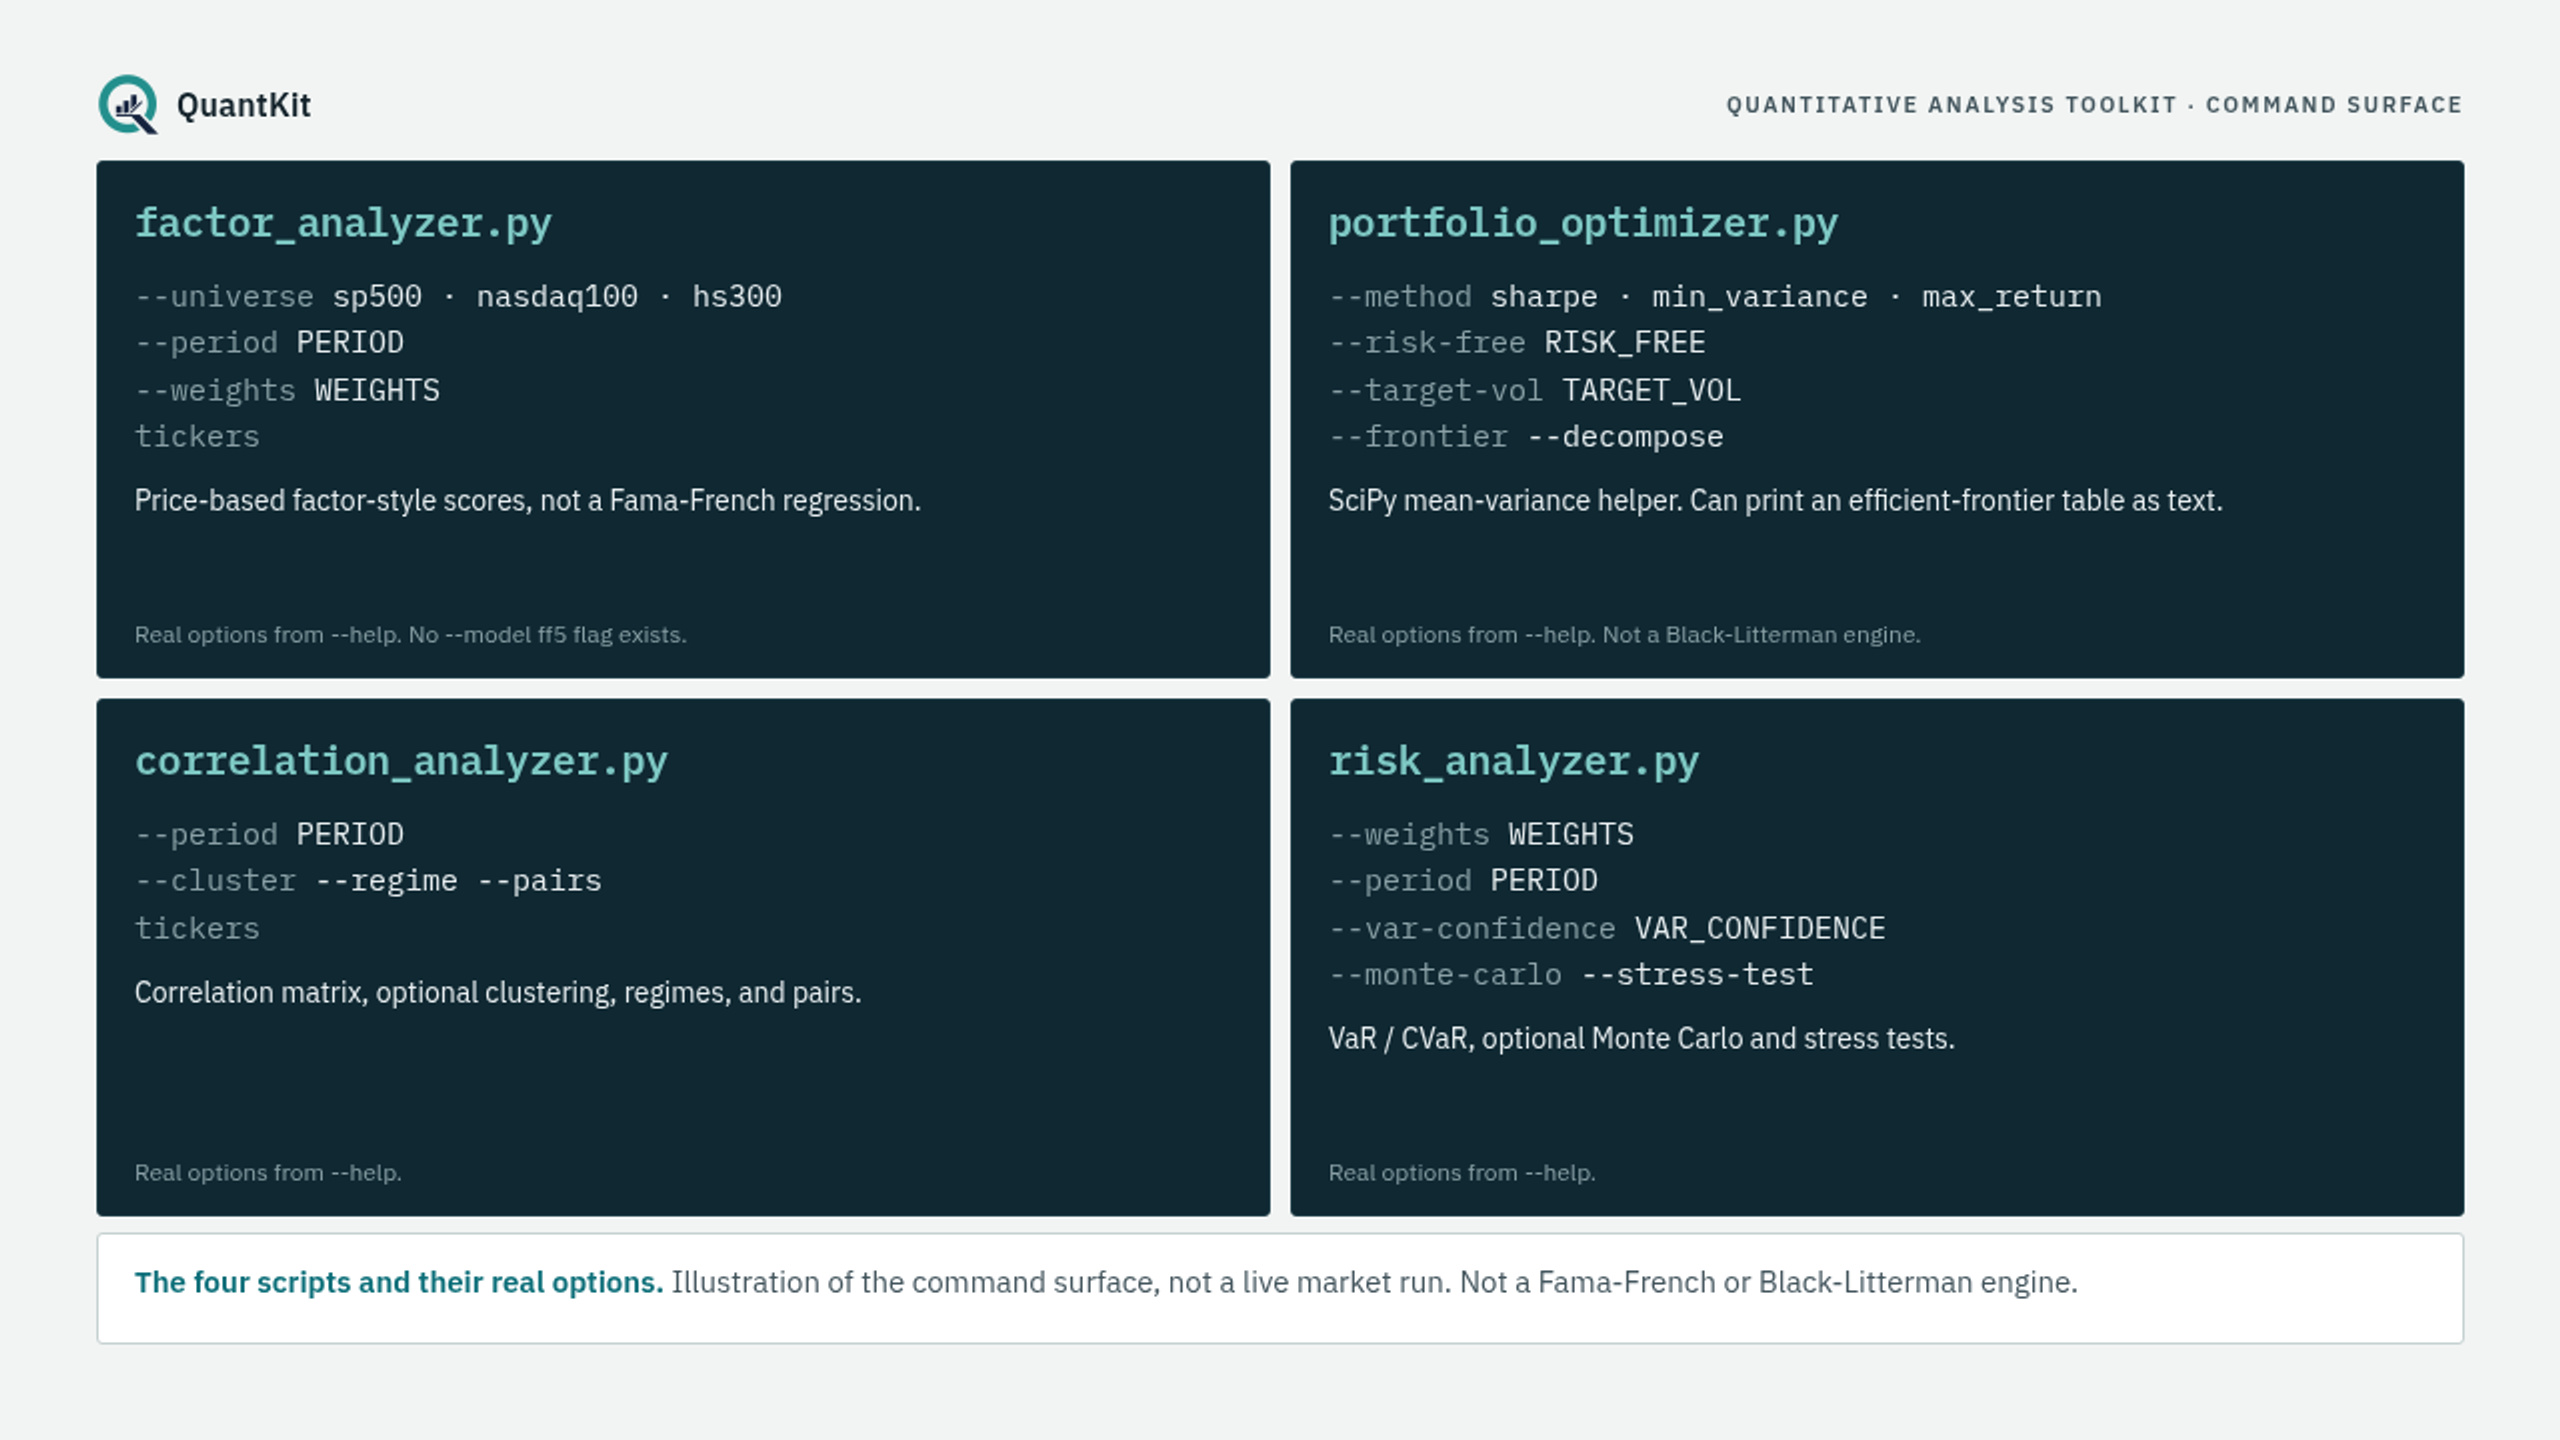
Four Python scripts: factor-style scores, mean-variance, correlation, VaR.
Four Python scripts for working with Yahoo Finance equity series (examples include US and Hong Kong tickers).
What you get:
• Factor-style scores (not a full Fama-French regression engine)
• A mean-variance helper (SciPy) that can print an efficient-frontier table as text
• A correlation helper
• Risk helpers for VaR / CVaR and a simple Monte Carlo
What it is not:
• Fama-French 3-factor / 5-factor, Black-Litterman, risk-parity, and cvxpy are not in the code. A short markdown note mentions Fama-French, but that is not an implemented model
• There are no time-series charts. Some documented CLI flags in factor_analyzer.py are unused