
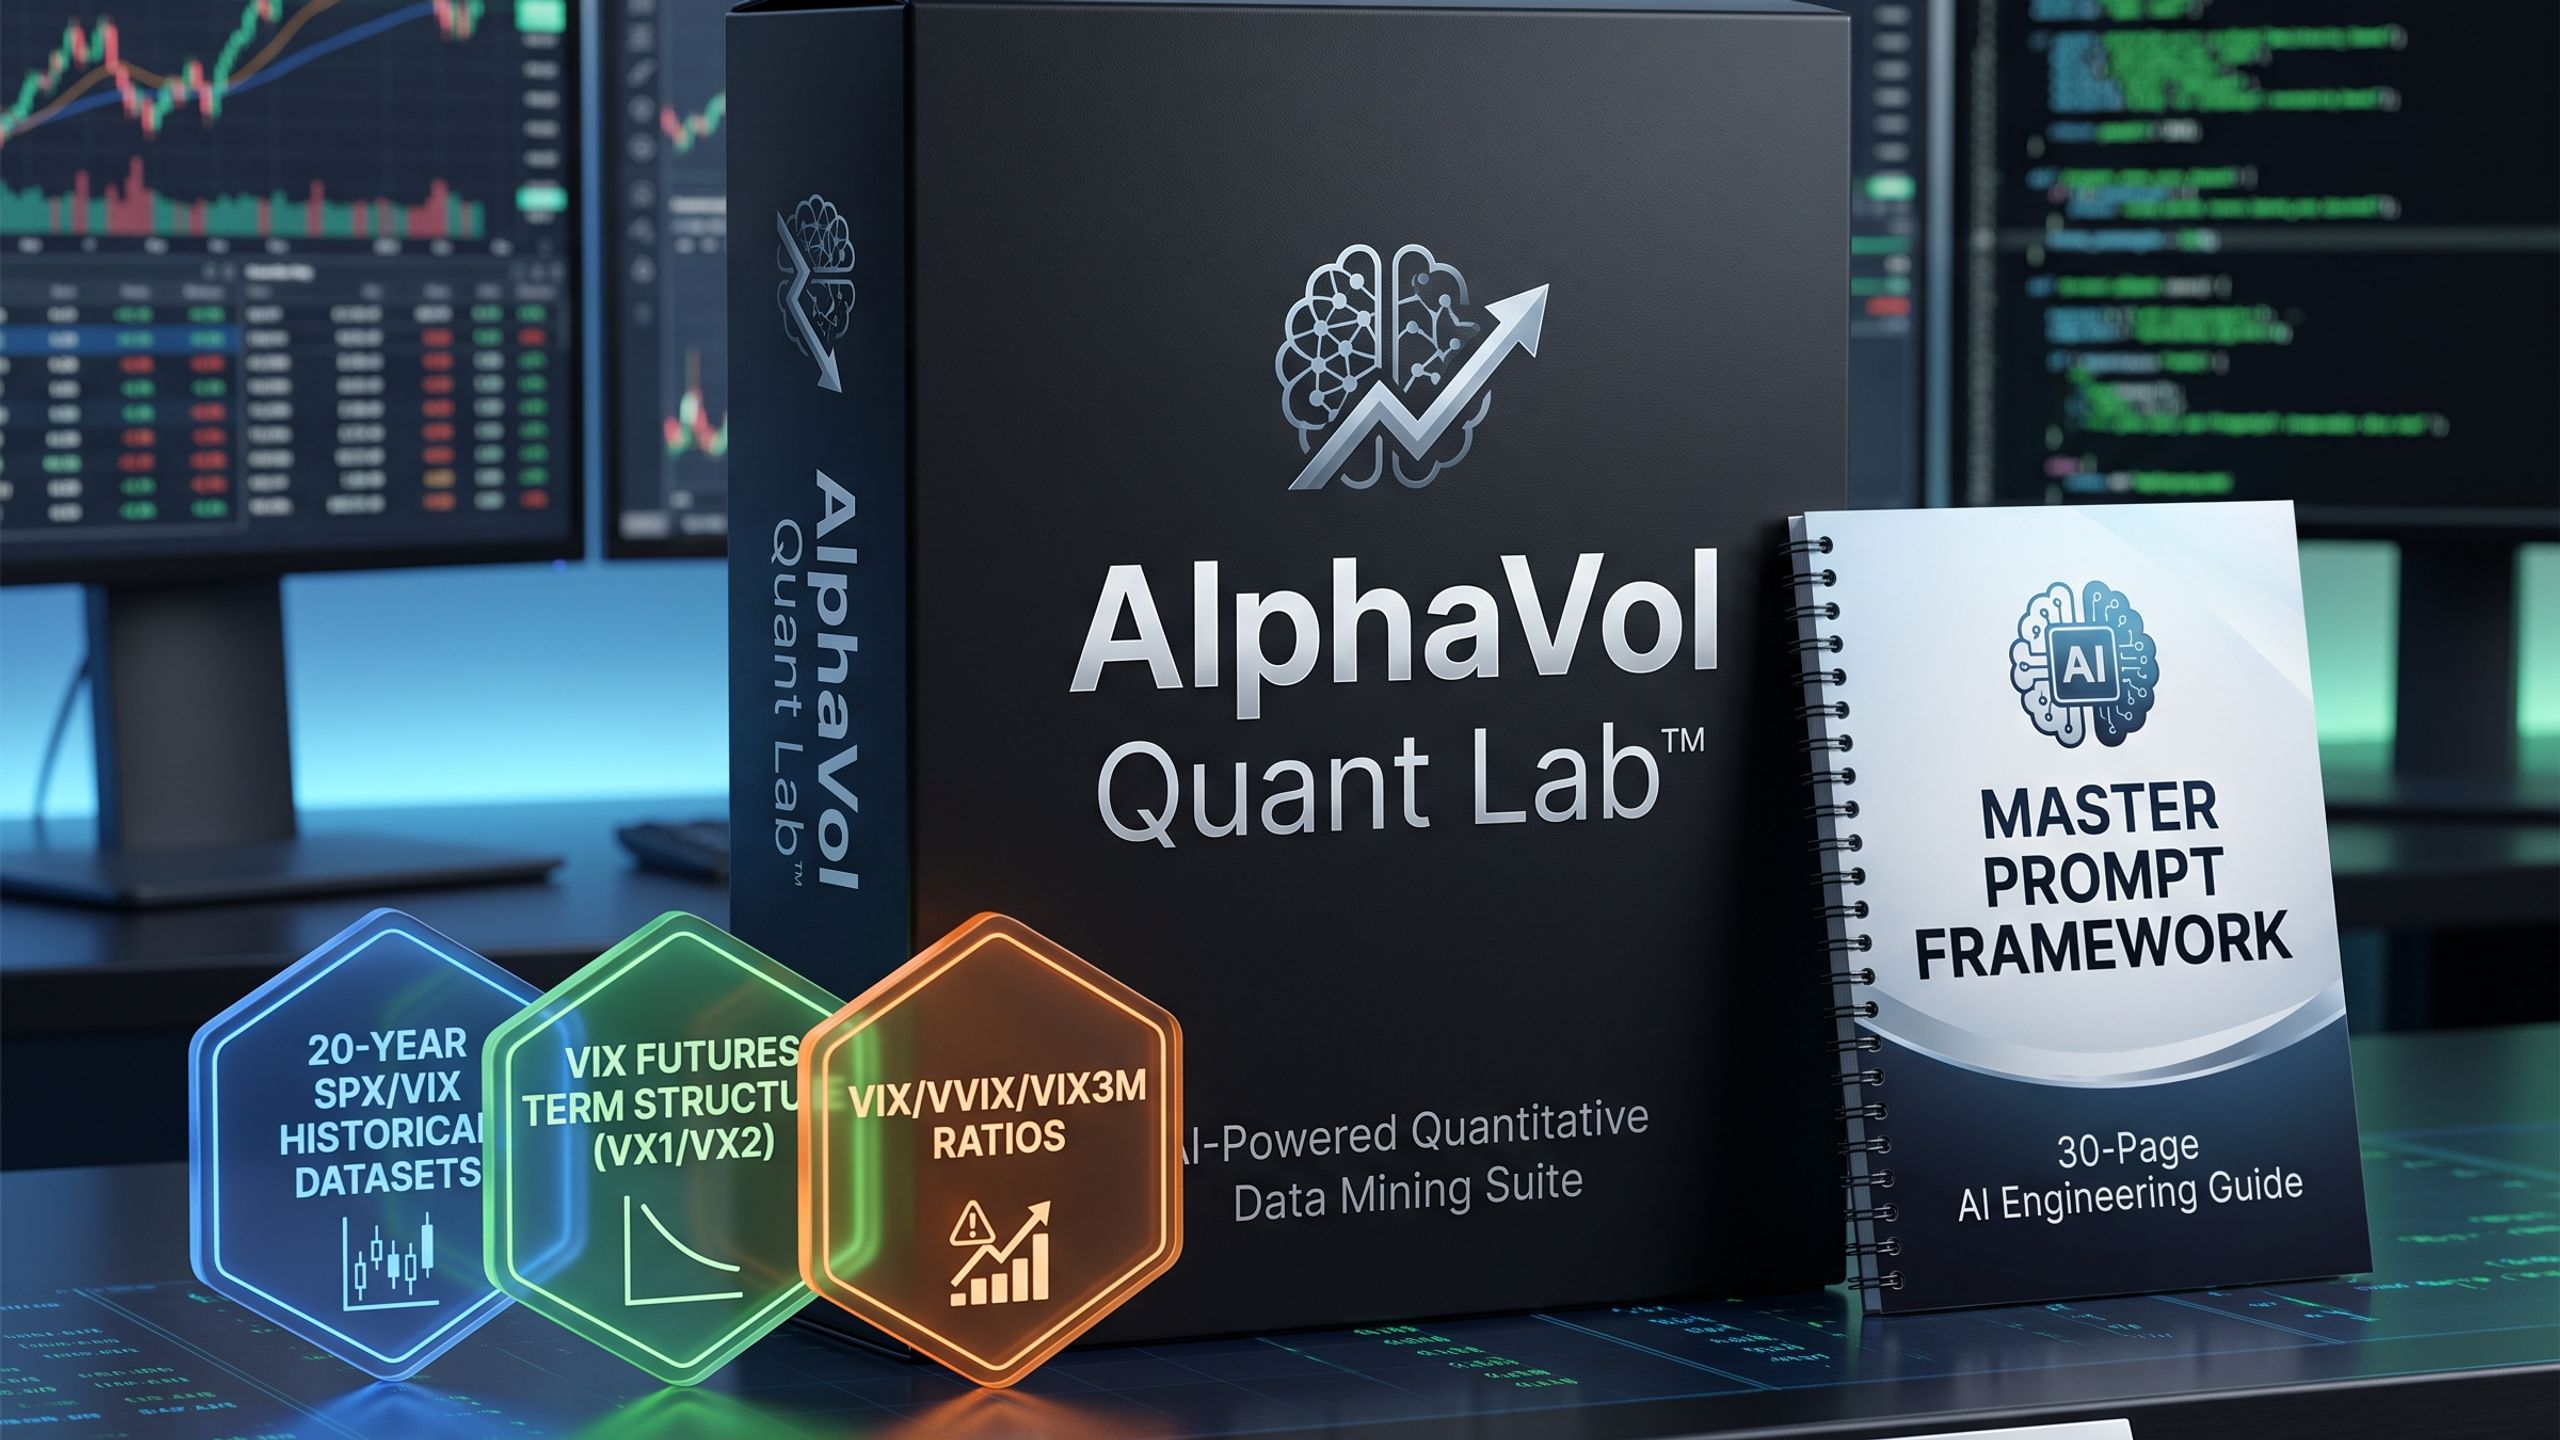
VolTerm Engine™: S&P 500 Volatility Data & AI Mining System
20 Years of S&P 500 Volatility Ratios for True Statistical Edges in Minutes.
A plug-and-play institutional research package containing two decades of proprietary S&P 500 volatility ratio datasets combined with a 30-page AI prompt engineering framework. It enables retail traders, quants, and algo developers to mine statistically significant market timing edges without coding from scratch.
The Problem
95% of retail traders lose money because they rely on laggy chart indicators (RSI, MACD) on single-price charts. Institutional quantitative funds don’t look at price alone—they look at Volatility Term Structure, Futures Contango, and Volatility-of-Volatility (VVIX) to predict crash drawdowns and asymmetric buy-the-dip entries before price moves.
However, gathering 20 years of clean futures and options volatility data costs thousands of dollars, and coding backtesting algorithms requires years of quantitative programming experience.
The Solution: AlphaVol Quant Lab™
AlphaVol Quant Lab™ provides the raw institutional data and the AI execution engine to run institutional-grade quantitative backtests instantly.
By feeding our proprietary datasets and 30-page prompt architecture into AI code interpreters, you can mine two decades of market regimes to generate precise, rule-based entry and exit signals with full statistical rigor ($p$-values, Sharpe ratios, and Out-of-Sample walk-forward validation).
- 4 months agoEverything I need on my daily time frames all in one. It's perfect.Written 16 days after purchase
- 6 months agoThe perfect way to track the NYSE / NASDAQ comp spread. Great jobWritten 5 days after purchase