



Midday read — Friday, September 25, 2026 · 1:10 PM ET
The three-day slide is over. S&P 7,738.86 (+0.45%), Nasdaq 27,078.13 (+138.76, +0.52%), Dow 51,745.04 (+395.06, +0.77%). VIX −4.0% to 15.04.
The Dow leads for the first time in a week, which is a shift worth noting — it's been the worst index every session since Monday. It's also a two-stage session: the index opened at 7,710, sank to 7,693 in the first forty-five minutes, then turned and has been climbing since. Buyers took the dip rather than selling the open. That's the opposite of what happened Monday through Thursday.
Microsoft is carrying it. MSFT +3.79% to $516.82 is doing outsized work in both the Dow and the S&P.
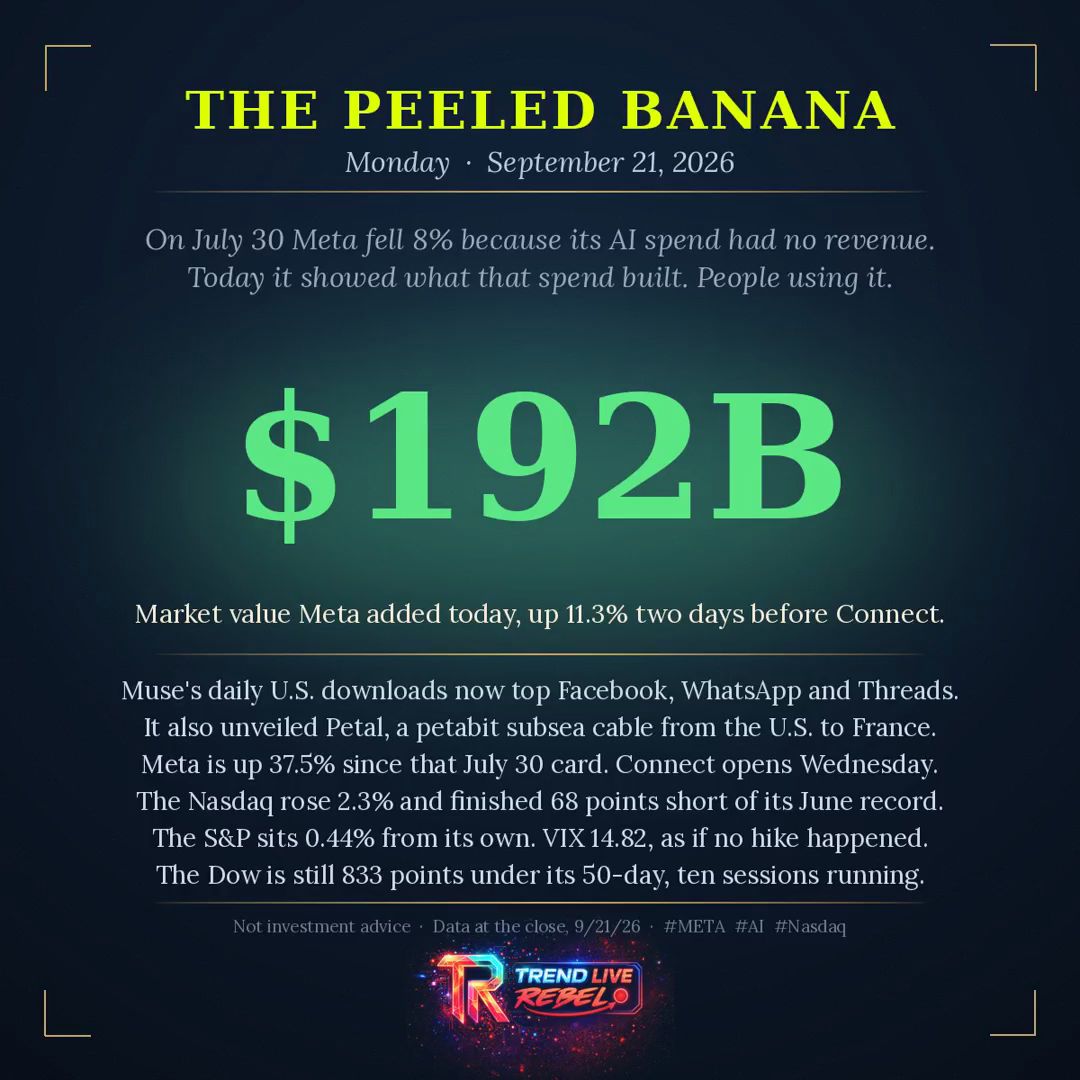
Meta is the offset. META −3.48% to $750.54, its first red session in six after a roughly 15% run off the Muse launch and Connect. Some of that is profit-taking on a stock that went nearly vertical.
The chips are flat and unhelpful: SMH +1.26%, MU +0.09% parked above $1,081, AMD +0.13%, NVDA +0.17%, INTC −2.21% the one real decliner. No leadership there either way.
Elsewhere: AAPL +1.14%, AMZN +0.43%, GOOGL +0.38% all modestly green; TSLA −1.58% and XOM −1.15% red.
Where the week lands: the S&P is about 1% off its record and roughly 110 points above the 50-day. The Nasdaq printed an all-time high Wednesday, sold it hard for two days, and has now recovered most of it. Volatility peaked near 16.6 yesterday and is back under 15.
Nothing resolved this week. The index is right where it started, just with more mileage on it.
🍌 See you all on the trading floor