



MIDDAY MARKET RECAP — Friday, October 9, 2026
S&P 500: 7,800.33, +0.45%
Nasdaq: 27,324.47, +131.13, +0.48%
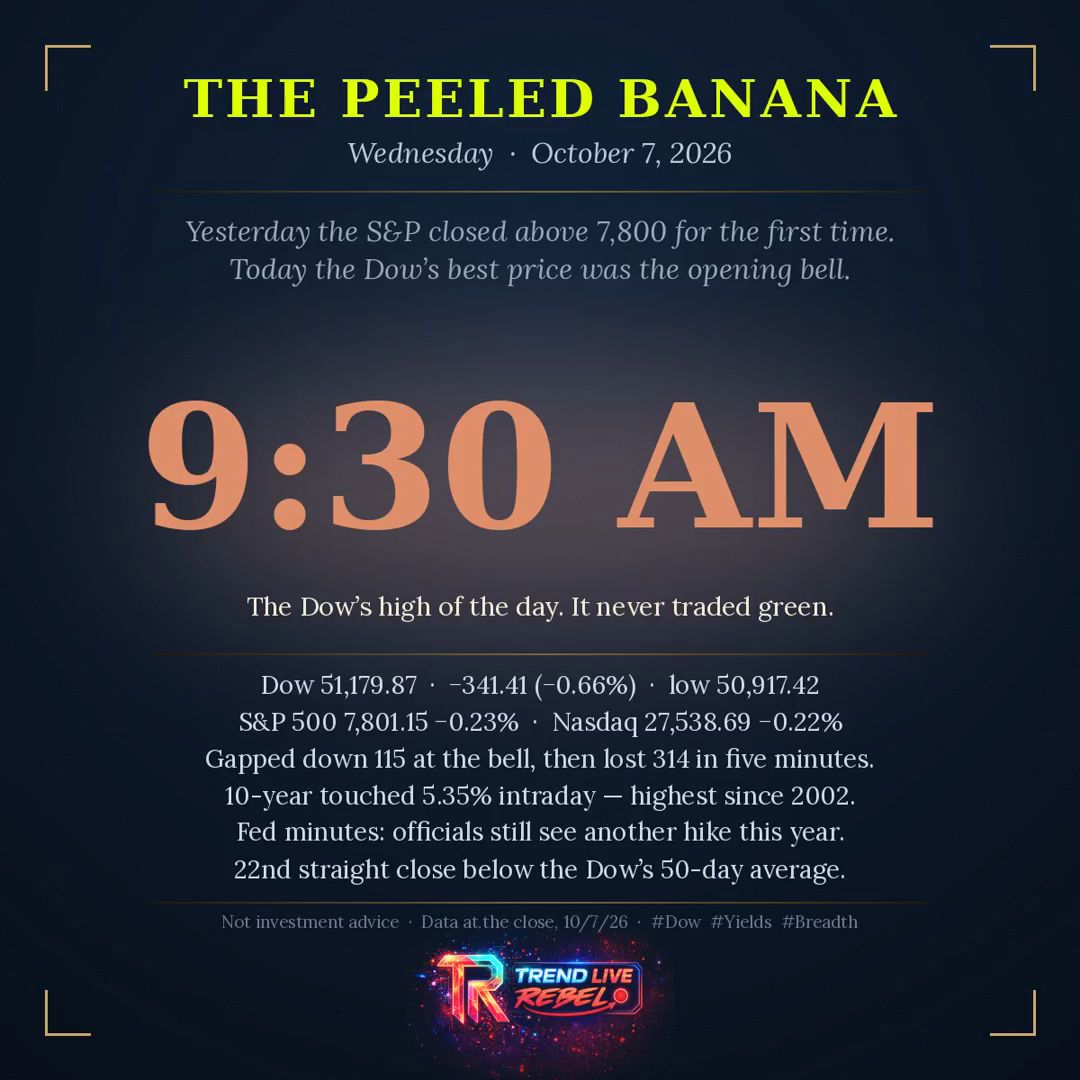
Dow: 51,486.93, +255.29, +0.50%
Green across the board and almost perfectly even — all three indexes within five basis points of each other. VIX down 3.2% to 14.92. On the surface, a clean bounce after two down days.
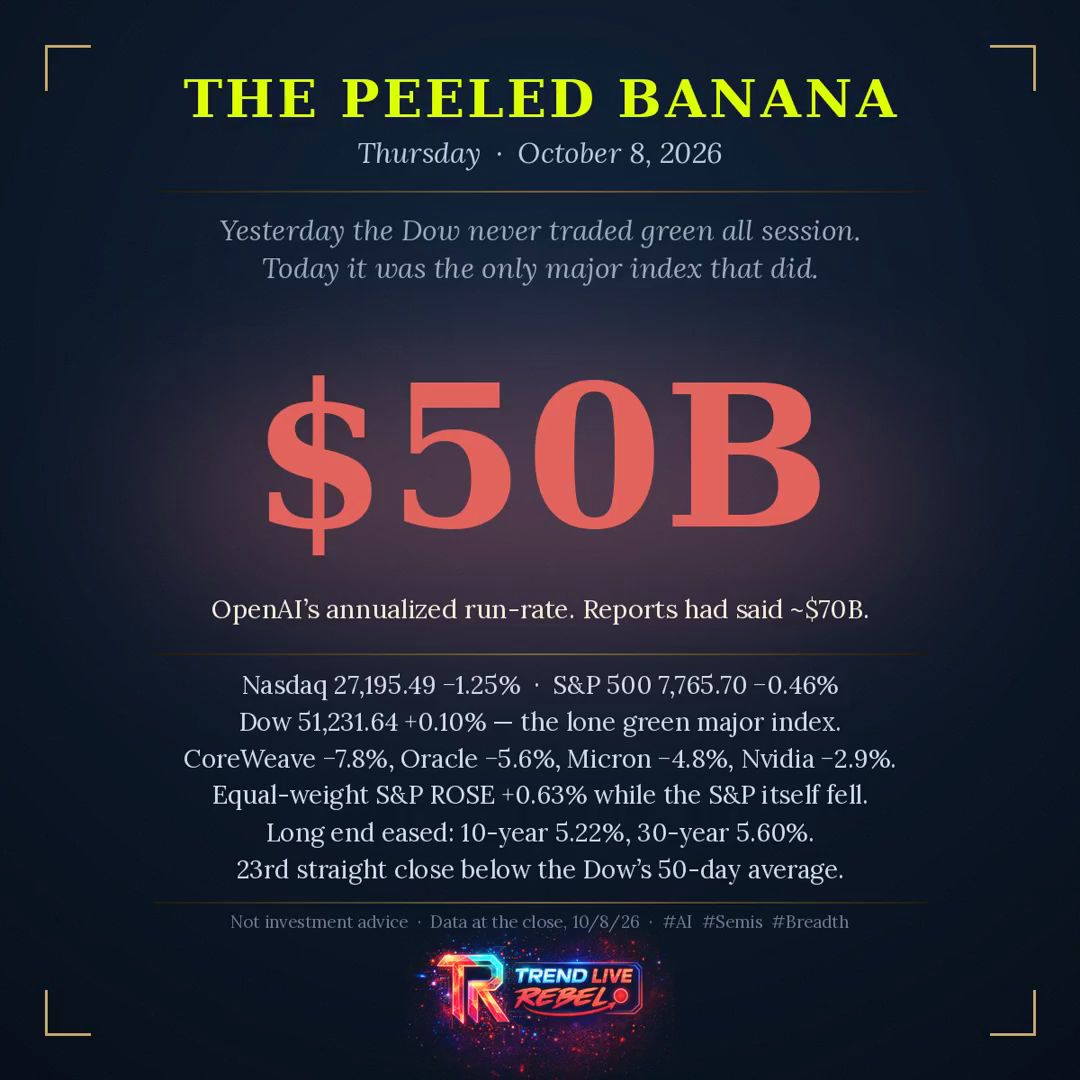
Underneath it, silicon did not come along. Micron is down 1.61% to $1,019.17, its third straight loss, and the four-figure handle I have been pointing at for two weeks is nineteen dollars away. AMD off 1.46%. Taiwan Semi off 1.37%. SMH down 0.61% on a day the Nasdaq is up half a percent. SanDisk red again, Intel red again. Three consecutive sessions of the chip complex lagging — and today it is lagging into strength, which is the version that matters.
The lifting is coming from software and mega-cap. Oracle up 4.89% to $141.80, best large-cap on the board. Palantir up 3.45% at $205.64, second straight day ignoring the rest of tech. Amazon +2.43%, Microsoft +2.19%, Alphabet +0.85%. Money is not leaving technology. It is moving from the companies that build the hardware to the ones that rent the output.
Everything else is quietly participating. Caterpillar, Deere and Eaton all green — Wednesday’s industrial wreckage is two days into repair. Energy holds, Exxon +0.99%. Gold +1.43%. Goldman and JPMorgan green. A broad, low-volatility advance with one conspicuous hole in it.
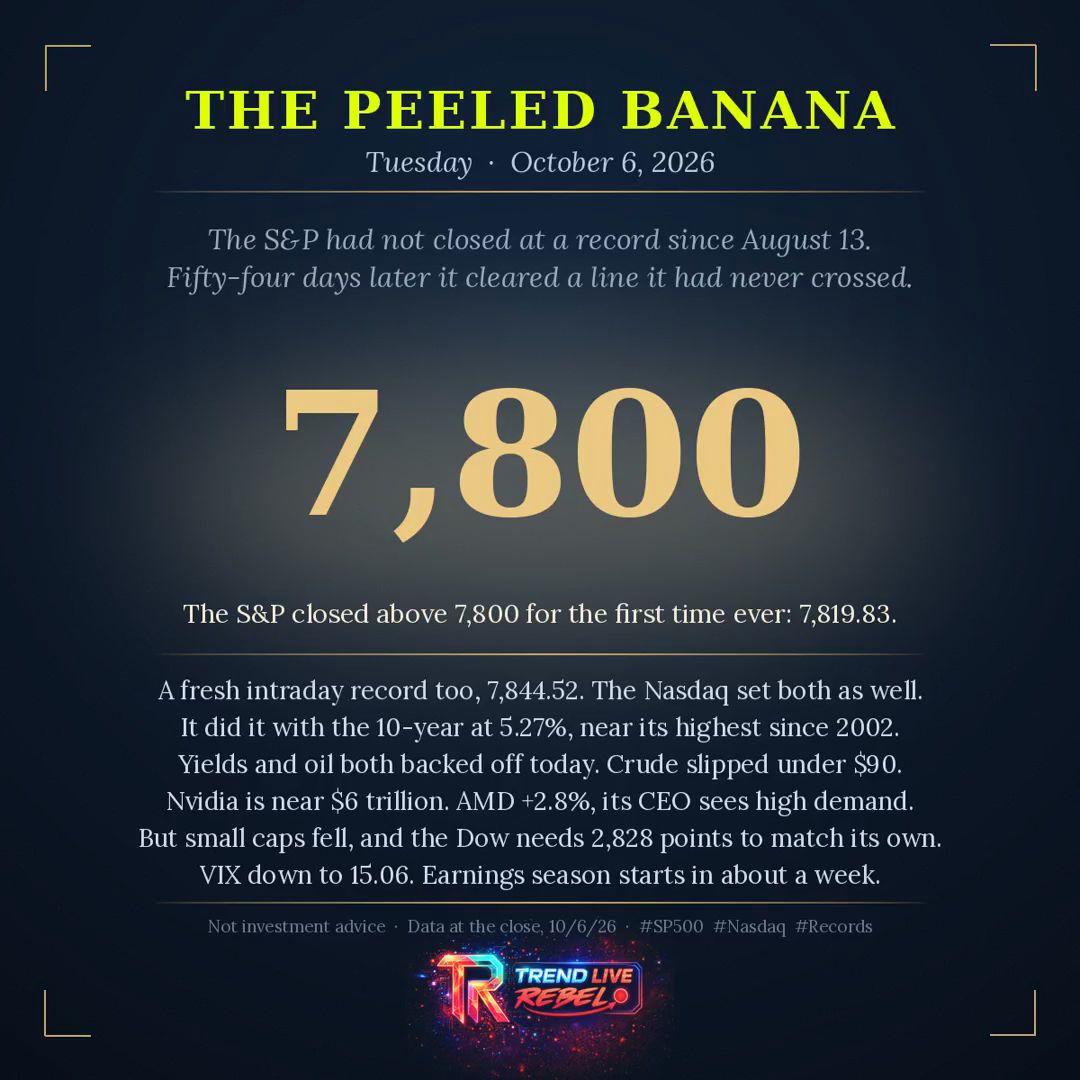
The S&P opened 7,786.36, dipped to 7,782 early, and has climbed a steady staircase since, tagging 7,805 before settling just under 7,800. The year high at 7,844.52 is half a percent overhead.
Into the close I want one thing: does MU hold four figures. A close under $1,000 after three down days turns a pullback into a trend, and it happens with the index near its high. That divergence does not resolve quietly.
The index is healing. The chips are not. Watch which one blinks.