Redirecting customers to an external checkout costs your platform more than lost sales. Learn how embedded checkout converts more buyers, adds new revenue streams, and keeps users on your platform.
Key takeaways
- Nickel lifted payment completion from 29% to 47% after moving to embedded checkout, so more of the same traffic turned into paid orders.
- Owning the payment flow creates new income streams: instant payout fees, premium tiers, upsells, and affiliate splits.
- Embedded payments lock in sellers, delight buyers, and build first-party data that slashes churn.
Embedded checkout increases platform revenue and retention by keeping the entire payment flow inside the product, instead of redirecting buyers to an external page.
This lifts conversion rates, opens new revenue streams like transaction fees, and builds the purchase history that keeps users from switching to a competitor.
The global embedded payments market is projected to grow more than tenfold, from $39.1B in 2025 to $430.3B by 2033 (a 35.5% CAGR), according to Grand View Research.
In this guide, you'll learn what embedded checkout is and how it helps platforms not only boost total revenue, but retain users at the same time.
What is embedded checkout?
Embedded checkout is a checkout integrated directly into a website, platform, or software product, rather than redirecting customers to an external page to complete payment.
So why the switch?
Embedding your checkout keeps the payment flow on-page, reduces customer drop-off, and ensures branding remains consistent.
But there's another big benefit: revenue. When you embed checkouts directly, you can take a share of every transaction processed, and that's where platforms can see huge uplift.
Here's a brief breakdown:
| Redirect checkout | Embedded checkout | |
|---|---|---|
| Customer experience | Buyer leaves your site to pay on a third-party page: new branding, extra steps, broken trust | Buyer pays without leaving your product: one continuous, on-brand flow |
| Data | Transaction data lives with the payment provider | You own first-party data: purchase frequency, AOV, churn signals |
| Revenue | Capped at your product's own pricing; drop-off at the handoff | Higher completion rates, plus a share of every transaction processed |
How does embedded checkout work for platforms?
Platforms typically integrate embedded checkouts via a provider's API or drop-in components. This allows the checkout to render inside the web or app interface natively.
The API handles account creation for users, checkout customization, fund routing between parties, payouts, and your platform's share of each transaction.
You configure how money moves (which payment methods are accepted, what goes to the seller, what goes to the platform, and on what timeline); the provider carries KYC, compliance, and the banking relationships. How much of that flow you build yourself depends on the provider you choose.
With Whop, you can drop in a prebuilt checkout component or checkout link and go live in minutes.
Or, you can create an embedded checkout flow using Whop's API for full control over routing, splits, and payouts.
We're building the first end-to-end API for running a business. Money movement, customer acquisition, and payouts all run through the same system your checkout does.
The three ways to embed a checkout
Platforms typically embed checkout in one of three ways:
- Drop-in components. A prebuilt checkout rendered inside your page (usually a secure iframe). Card data goes straight to the provider, keeping you in the lightest PCI bracket (SAQ A). This is the paste-in-and-launch option.
- Hosted fields. Individual payment inputs you arrange inside your own UI. More design control, slightly more compliance scope (SAQ A-EP).
- Full API. You build the entire flow and control routing, splits, and payouts programmatically. Maximum control; the provider still carries processing compliance, but your integration surface is bigger.
Whop supports drop-in components and gives you full API access, so you can ship today or build invisible infrastructure.
How much do checkout redirects cost your platform?
Checkout redirects cost platforms sales because every handoff to a third-party page adds friction: new branding, an extra page load, and re-entered payment details.
Baymard Institute found that 19% of shoppers abandon checkout because they don't trust the site with their card details, and 17% because checkout is too long. A redirect sends buyers to an unfamiliar page to pay, and adds an extra step to get there.
The numbers back this up: when Nickel moved its payments onto Whop's embedded checkout, payment completion rose from 29% to 47%, an 18-point jump on the same buying intent.
So let's break that down in terms of real money, using Nickel's numbers as the test case.
Say your platform generates 10,000 checkouts a month at a $50 AOV (average order value). At 29% completion, you're looking at 2,900 completed orders and $145,000 in monthly GMV (gross merchandise value).
Switch to embedded checkout, see the same lift Nickel did, and that traffic converts at 47%: 4,700 completed orders and $235,000.
If your platform takes a 10% fee on each sale, that's the difference between $14,500 and $23,500 in platform revenue each month. That's a 62% lift from traffic your sellers already earned.
Over a full year, the improved conversion is worth an extra $108,000 to you, before a single new seller signs up.
That's the point a lot of platforms miss. Every abandoned checkout is a double loss. Your seller loses the sale, and you lose the fee.
Do that to a seller enough times and they don't just earn less, they leave for a platform where their buyers actually convert.
How to work out what redirects are costing you:
- Pull 30 days of checkout starts and completions from your analytics.
- Divide completions by starts: that's your current completion rate.
- Choose a lift to model. Nickel's was 18 points; halve it for a conservative case.
- Multiply your monthly checkout starts by that improvement and your AOV. That's the GMV you're currently losing at the handoff.
Embedded checkout has perks third-party payment pages can't give you
Removing the redirect is only the baseline. Embedding checkout also unlocks:
- Saved payment methods: Returning buyers check out in one click instead of re-entering card details.
- BNPL at checkout: Buyers split the payment; you get paid upfront.
- Local payment methods and adaptive pricing: Buyers see prices in their own currency and pay with the payment method they're used to, including Apple Pay and crypto.
- Smart payment routing: If a payment fails, it's automatically retried with another provider instead of dying on the spot.
Whop's embedded checkout builds all of this in. Purchases stay on your domain, with BNPL, crypto, and payment orchestration already configured.
Unlock new revenue streams with embedded checkout
Beyond taking a cut of each transaction you facilitate, platforms can also introduce new revenue streams when embedding checkout. These include instant payout fees, premium checkout features, upsells, and affiliate splits.
Instant payout fees
Embedded checkout puts your platform in control of the money flow. Sales settle inside your system, which means you also decide when sellers get paid.
That control is monetizable, because sellers will often pay to get their money faster.
According to research from PYMNTS, 40% of millennials would be willing to pay for instant payouts, even when they can wait more than a week to receive the funds. Only 29% of Gen Z would be willing to pay when they can wait.
And that's if they can wait. For most sellers, time is of the essence and revenue is needed ASAP. That's where instant payout fees can drive platform revenue higher.
Just remember, it's best to keep instant payouts as an opt-in upgrade. 65% of payout recipients say they're more likely to do business with a platform that offers instant payouts but lets them wait for free. Force the fee, and that drops to 24%.
Premium checkout features
While basic checkout should come free for sellers, premium checkout features can also be the reason sellers upgrade to a higher paid tier.
Take Shopify, for example: higher plans come with lower card rates, and full checkout customization is reserved for Shopify Plus. Sellers doing bigger volume upgrade the moment the math makes sense.
The features worth gating are the ones that grow with a seller's success. Lower transaction fees at higher plans, advanced payment methods like BNPL, white-labeled checkout branding, recurring billing and payment plans, or abandoned-checkout recovery and conversion analytics.
Order bumps and upsells
Configuring embedded checkout to have an order bump or upsell feature is a win for platforms and sellers alike.
Order bumps are one-click add-ons that appear at the point of payment. Say a customer is buying a course, and the seller also offers a workbook. An order bump can ask if they'd like to add the companion workbook for $9. It often converts because the buyer's already committed; saying yes only takes one tap.
Higher AOV means more profit on both ends. By building this into your checkout system, you increase order value for sellers, and give your platform a bigger cut.
Affiliate splits
Affiliates help promote a seller's product to their own audience and earn a commission each time someone buys. Without automation, this can get messy. When it's built into checkout, it's seamless.
For platforms, every affiliate-driven sale increases GMV. You earn your normal cut, and your seller doesn't have to spend as much on ads.
Say a $100 sale comes through an affiliate link. In this example, the seller offers a 20% commission and your platform takes a 10% fee. An embedded checkout with split routing capabilities pays out automatically:
- $20 to the affiliate
- $10 to your platform
- $70 to the seller
That $100 came from a buyer the seller might have never reached. So the sale is new GMV, and your $10 is revenue that you would not have earned otherwise.
This is a native feature on Whop embedded checkouts. Just pass an affiliate code into the embed, and the commission splits automatically across every sale it drives.
There's no code inventory to manage, either: an affiliate's account identity is their code, so onboarding the ten-thousandth affiliate is no different from the first.
Use embedded checkout to improve platform retention
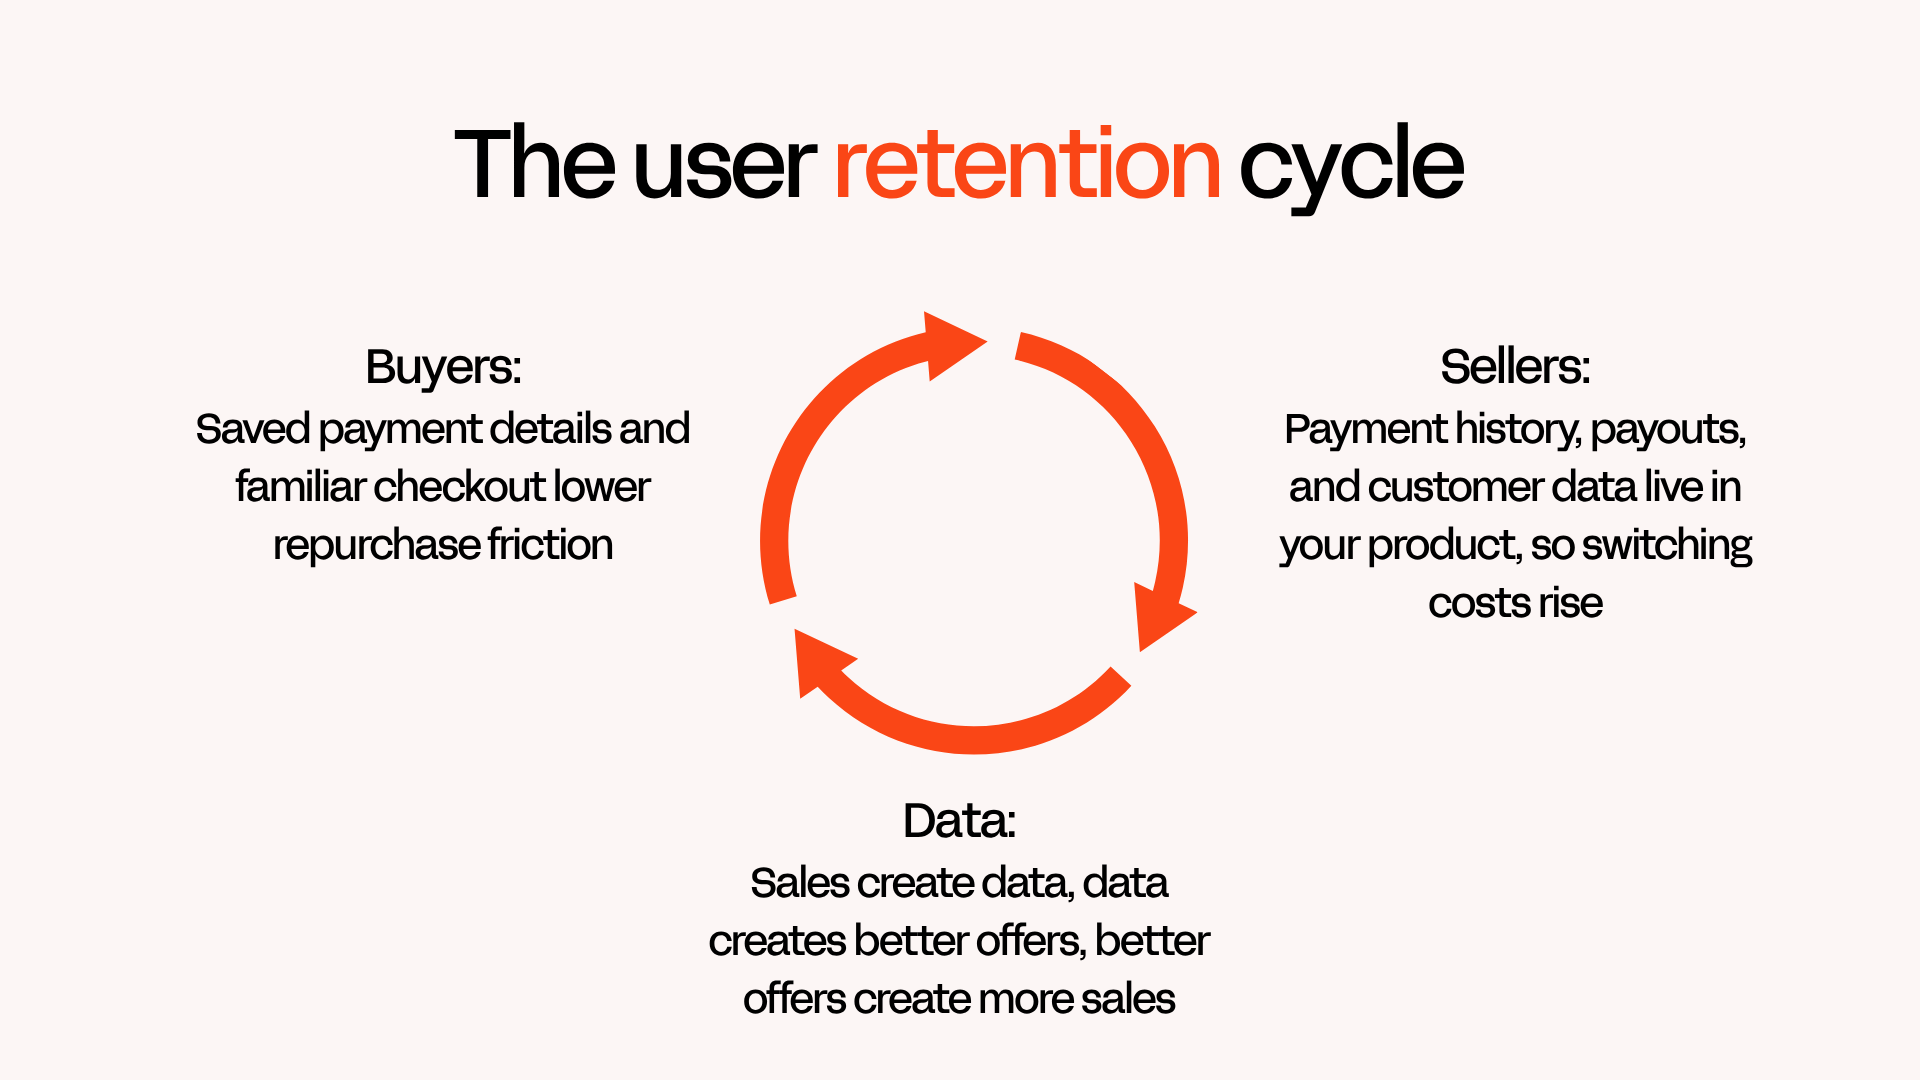
Embedded checkout improves retention by making your platform the place where buyers' saved details, sellers' payout history, and your transaction data all live.
Keeping customers and sellers on-platform is central to GMV and growth.
J.P. Morgan's Sector Spotlight: Embedded Payments 2025 report models what that can look like. In its illustrative scenario, a software company uses its payments revenue to lower its subscription price by up to 10%. The cheaper bundle is harder to leave, and payments revenue more than covers the discount. As a result, annual churn falls from 15% to 5% over five years, and its LTV:CAC ratio climbs from 1.0x to 3.6x.
Platforms can do the same. Use your transaction revenue to lower seller fees or offer a free starter tier. Sellers pay less, and they lose that discount if they leave.
The Boston Consulting Group (BCG) found that more than half of relevant vertical software vendors in North America offered embedded payments in 2025. Sellers have noticed. In Adyen and BCG's research, 86% of SMBs plan to move to platforms with embedded payments, and 97% say embedded payments improved their satisfaction with their platform. So, shipping without embedded checkout is now the riskier choice.
What a 10-point churn gap is worth
Take the churn figures from J.P. Morgan's scenario above and apply them to a platform. Let's say that you have 1,000 active sellers, and each one earns you $200 a month in fees, or $2,400 a year.
At 15% annual churn, you're down to about 614 of those sellers by the end of year three. At 5%, you still have about 857. That's 243 more sellers still transacting, from the same starting base, without spending another dollar on acquisition.
In year three alone, that's the difference between $1,473,600 and $2,056,800 in platform revenue: an extra $583,200 a year. And it doesn't stop there: the gap continues to grow every year after that, because the sellers you keep are the ones already driving volume.
Embedded checkout helps retention threefold: buyers keep coming back for the convenience, sellers stay because switching providers isn't worth the hassle, and your data becomes more valuable with every sale.
What to consider when choosing an embedded checkout provider
To maximize revenue and retention for your platform, choosing the right provider for embedded checkout is key.
Here are the main areas you want to scope:
Conversion features
Conversion features on embedded checkout include saved payment methods, one-click checkout for returning buyers, local payment methods and currencies, and a flow that actually works on mobile. A checkout that embeds but doesn't convert solves nothing.
Whop offers 100+ local payment methods, upsell features, saved payment methods, and more conversion boosters like BNPL.
Compliance
Payment acceptance means PCI scope, card network rules, and dispute handling become front and center. Find out which of those the provider takes on and which stay with you and your sellers.
Data access
To make the most of your data and feed your retention loop, you need to be able to access it. Some embedded checkout providers treat your data as theirs, so make sure the provider you go with makes it fully accessible to your platform.
Time to go live
Some providers need months of integration work before you can process a single payment, which can cost you a full quarter (or more) of the revenue lift you're building toward.
The best providers give you options: a prebuilt embed you can paste in and launch the same day, or an API you can build on in days when you want more control.
Cal.com embedded Whop's checkout to upgrade from SaaS to fintech, allowing the platform to earn revenue on every paid booking – with no integration issues.
"Very happy for this partnership. Technically was a breeze to integrate."
Keith Williams, Head of Engineering at Cal.com
Embed checkout with Whop and boost revenue and retention at once
Embedded checkout is one of the cheapest growth levers platforms can pull.
Introduce it, and you'll see fewer redirects, higher conversions, bigger profits, and more stickiness. It's one simple upgrade that has benefits spanning your entire business, and it's how platforms earn their share of the internet economy.
Whop makes embedding checkout fast and simple, whether you opt for the prebuilt component or the API (when you want full control over routing, splits, and payouts).
Either way, BNPL, crypto, smart payment routing, and affiliate splits come with it.
Embedded checkout FAQs
How do I embed a checkout directly into my app or website?
The fastest way to embed checkout directly is to paste in a prebuilt component so that the checkout renders inside your page as a secure frame with no redirect. Whop lets you drop a one-click checkout button that displays a single Apple Pay, Google Pay, or Whop Pay button anywhere with one script tag.
What's the difference between embedded checkout and a hosted/redirect checkout?
Embedded checkouts keep your buyers on your platform throughout the entire payment process, while redirected/hosted checkouts send customers to an external page run by your payments provider. Keeping customers on your own platform has many benefits, including branding control, higher conversion rates, and more trust.
Does embedded checkout increase conversion rates?
Yes. Keeping buyers on-page removes the redirect, which is one of the biggest points of drop-off. When Nickel moved to Whop's embedded checkout, payment completion rose from 29% to 47%.
What's the difference between embedded checkout and embedded payments?
Embedded checkout is the buyer-facing piece: the payment form living inside your product. Embedded payments is the broader system behind it that incorporates fund routing, payouts, splits, and compliance. Embedded checkout is usually the first embedded payments feature a platform ships.
How do platforms make money from embedded checkout?
Platforms make money from embedded checkout by taking a cut of every transaction. This can be boosted by introducing premium checkout features for sellers, like adding financing options, instant payouts, and upsell configurations.
How long does it take to add embedded checkout to a platform?
With a prebuilt component, the same day: paste the embed, connect your account, and process a live payment. A full API integration with custom routing and splits typically takes days, not months. Anything quoted as taking a quarter or more is a provider problem, not an embedded checkout problem.
Is embedded checkout secure/PCI compliant?
Embedded checkouts are secure, but compliance depends on your provider and their specific terms.
Whop's embedded checkout loads as a secure frame inside your page, so card details never touch your servers. That architecture is what keeps sensitive payment data out of your systems, and out of your compliance burden.